

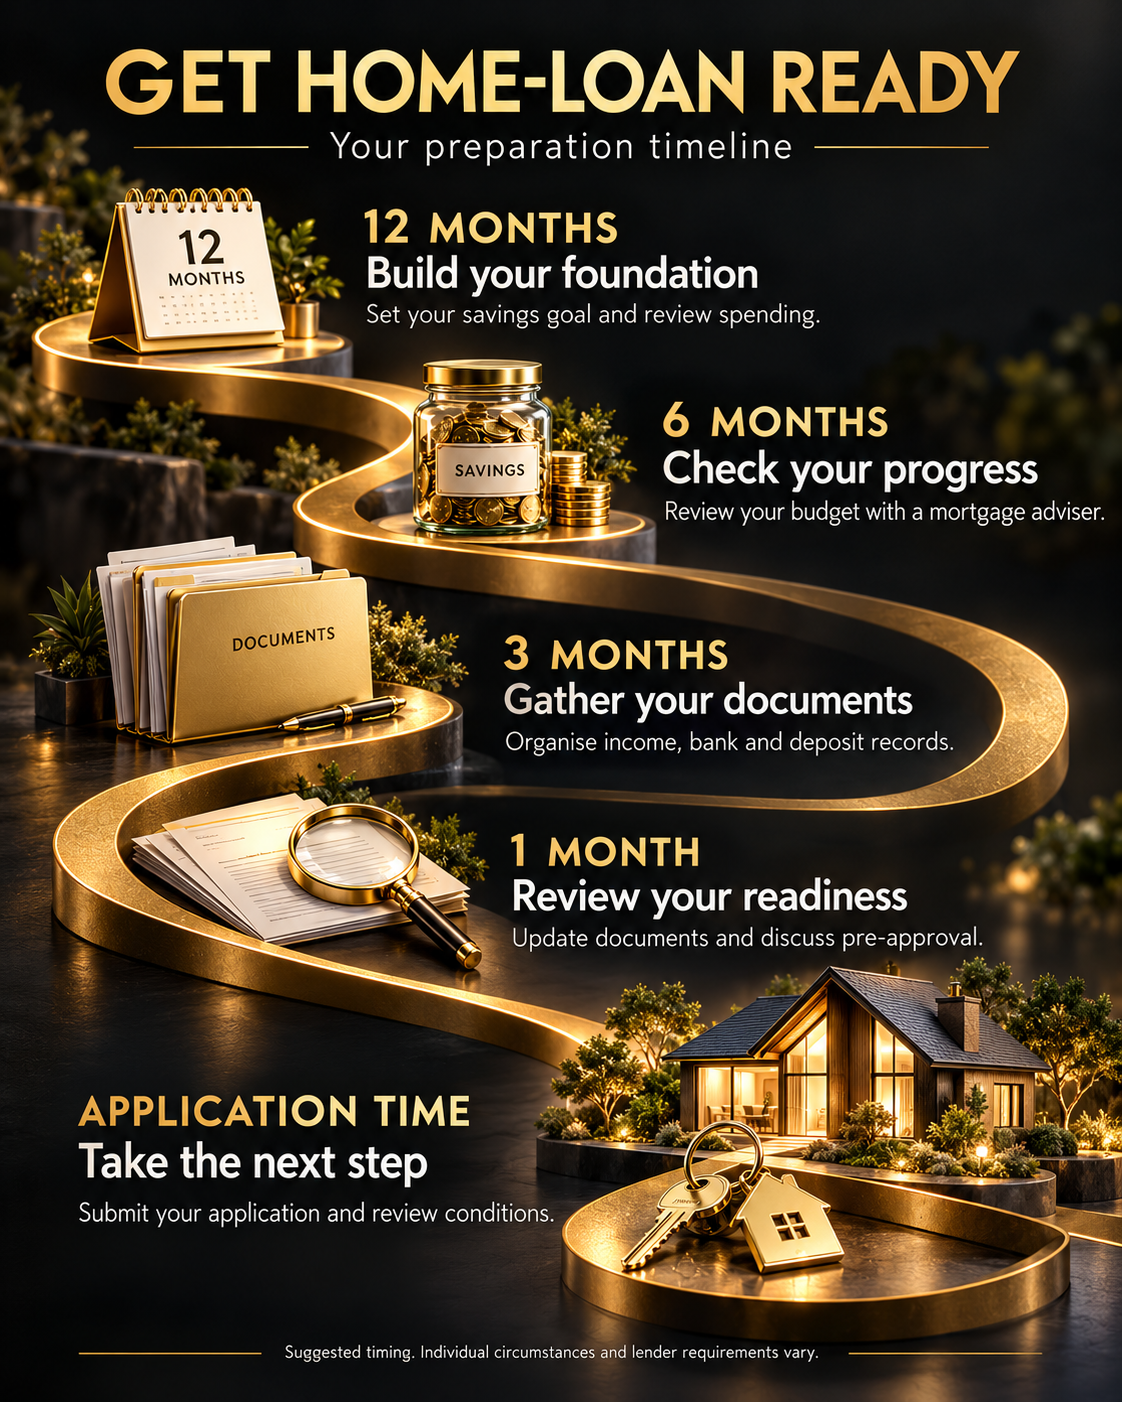
A simple, comprehensive guide to preparing your finances, applying with confidence and reaching settlement in New Zealand.
uying a home involves more than saving a deposit and choosing a property. You also need to understand your budget, organise financial records, compare lending options and prepare for the legal steps.
Starting early gives you time to make changes without rushing and spot issues before they become a problem.
12 months before applying
Build your foundation
Decide what you are preparing for
Think about the property type, location and timing that would suit your household. Separate your needs from preferences: a manageable commute may be essential, while an extra bedroom may be something you can compromise on. Research prices, but do not treat an online borrowing estimate as a confirmed budget.
Understand your starting position
Write down your income after tax, savings, possible deposit sources, debts, repayments, credit limits and household expenses. Include expected changes to work or family circumstances.
If you are buying with someone else, do this together. Discuss how you will share the deposit, repayments and other costs. Ask your lawyer whether an ownership agreement would be appropriate.
Build a realistic budget
Review actual transactions. Include groceries, transport, rent and bills, plus less frequent expenses such as vehicle servicing, insurance renewals, school costs and family commitments. Work out what you can consistently save after meeting your obligations.
Set a deposit target
Your deposit is your contribution toward the purchase. The home loan covers the balance, subject to approval. For illustration, a $700,000 property with a $140,000 deposit would require a $560,000 loan before other borrowing or costs.
The required deposit depends on the lender, property and your circumstances. Ask about your options rather than assuming everyone needs the same percentage. Saving $250 a week adds $13,000 over 52 weeks, before interest.
Allow for buying costs
- Legal and conveyancing fees.
- Building inspections, property reports and any required valuation.
- Insurance and moving costs.
- Rates or other settlement adjustments.
- Essential repairs, household purchases and an emergency buffer.
Obtain quotes as your plans become clearer. Avoid committing every dollar to the deposit.
Check your credit reports
Look for incorrect details, unfamiliar accounts or overdue payments. Request corrections where needed and keep commitments paid on time. You can normally request your credit report for free. Discuss past credit problems early rather than waiting for the lender to find them.
Check KiwiSaver early
Ask your provider about first-home withdrawal eligibility, the amount available, documents and processing times. Eligible members may be able to withdraw some savings after at least three years in KiwiSaver. Do not assume the full account balance can be withdrawn.
6 months before applying
Strengthen your finances
Check your savings progress
Compare actual savings with your target. If you regularly withdraw savings to pay bills, revisit the budget. Keep records of savings and other deposit sources.
Make a debt plan
List each balance, interest rate and repayment. Ask your adviser which debts to prioritise and whether reducing or closing unused credit facilities may help. Keep written confirmation of closed accounts. Avoid using all your cash without considering the deposit and emergency buffer.
Give your future budget a practice run
Estimate the mortgage repayment plus rates, insurance, maintenance and body corporate costs where applicable. Compare this with current housing costs. If affordable, save the difference. This helps test the budget and build savings, but does not replace the lender’s assessment.
Discuss income that needs explanation
Raise casual hours, overtime, bonuses, commission, contract work, self-employment, recent job changes, parental leave or multiple income sources. Different lenders may assess these differently.
Prepare self-employed records
Talk with your accountant about keeping financial records current. A lender may request financial statements, tax returns or assessments, business bank statements and recent trading information. Confirm the period and format required.
Clarify family help
Confirm whether assistance is an unconditional gift, a repayable loan or part of a guarantee or other arrangement. Do not describe borrowed money as a gift. Ask about independent legal advice so everyone understands their obligations.
Have an early mortgage conversation
You can speak with an adviser before you are ready to apply. An early review helps identify possible obstacles, useful next steps and a realistic timeline. It is a preparation discussion, not a promise of approval.
3 months before applying
Get organized
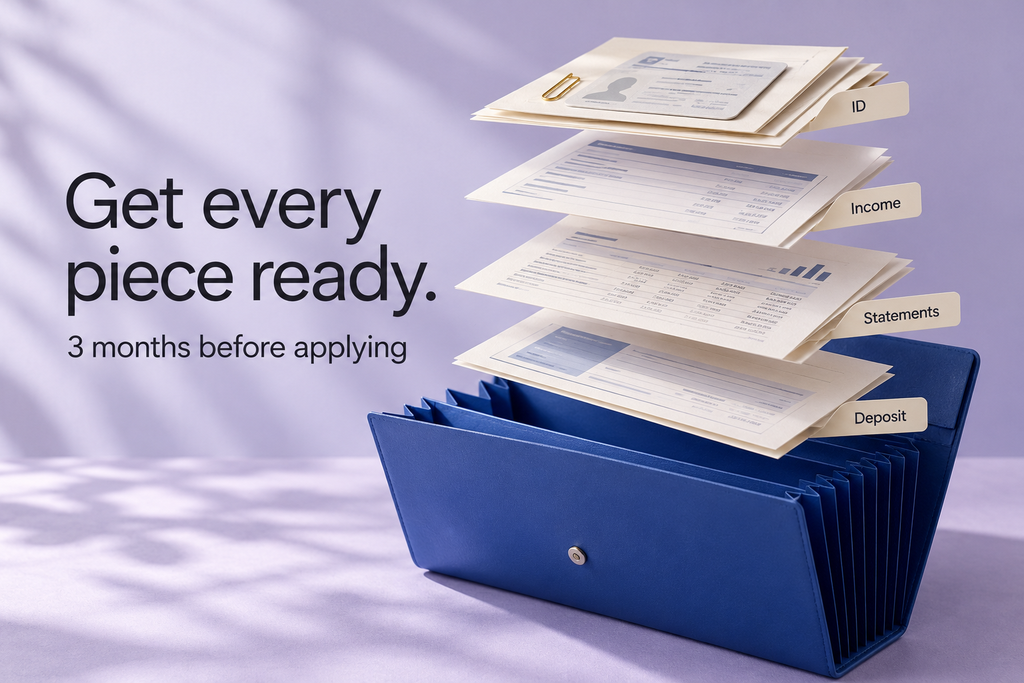
Build your application folder
Keep complete documents with clear file names. Use the lender’s tailored checklist: document requirements and periods covered vary.
| Category | Examples to prepare |
|---|---|
| Identity and residency | Accepted current ID and relevant citizenship, residency or visa documents. |
| Employment and income | Employment agreement, recent payslips and evidence of other income. |
| Banking | Complete statements for requested accounts. |
| Debts | Loan statements, credit limits and repayments. |
| Deposit | Savings records, gift evidence and other source documents. |
| KiwiSaver | Provider information about eligibility and available funds. |
| Self-employment | Financial and tax records requested by the lender. |
| Expenses | Accurate household budget and ongoing commitments. |
Make your deposit easy to explain
Keep evidence of large transfers, gifts, asset sales and overseas funds. Where money moves between your own accounts, retain the full statement trail. Avoid unnecessary transfers that make the source harder to follow.
Set your own spending limit
The maximum a lender may approve and the amount you feel comfortable repaying can differ. Allow for future childcare, study, travel, reduced hours and other goals.
Arrange a lawyer or conveyancer
Do this before making an offer. Discuss fees, availability, ownership arrangements and checks needed for the property types you are considering. Raise any questions about your legal eligibility to buy property in New Zealand.
Learn the main terms
| Term | Simple meaning |
|---|---|
| Principal | The borrowed amount still to be repaid. |
| Interest | The cost charged for borrowing. |
| Loan term | Total time allowed to repay the loan. |
| Fixed-rate period | Time during which an agreed rate applies. |
| LVR | The loan compared with the lender’s accepted property value. |
| DTI | Total debt compared with gross annual income. |
| Pre-approval | A lender’s conditional indication of available finance. |
| Settlement | Completion of the funds and ownership arrangements. |
A lender considers more than one measure. A deposit percentage or income figure alone does not determine approval.
Application
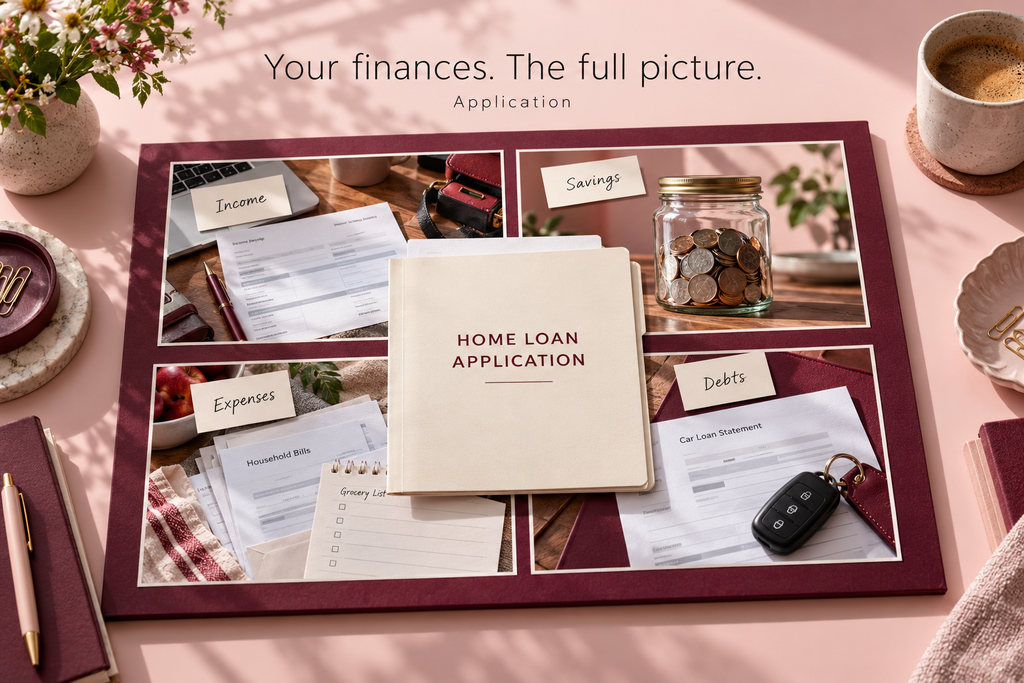
Present the full picture
Understand who does what
Your mortgage adviser helps you prepare, compare suitable options and communicate with lenders. The lender assesses the application and decides whether to offer finance. Your lawyer advises on legal matters and handles the property transaction.
Provide complete, accurate information
Disclose relevant debts and commitments, including those paid from other accounts. Explain unusual transactions, variable income and recent changes when asked. Submit full statements: screenshots or edited extracts may not show everything required.
Know what is being assessed
- Your identity and eligibility.
- Income and its reliability.
- Expenses, commitments, debts and credit history.
- The deposit amount and source.
- Your ability to meet repayments.
- The property offered as security.
Respond promptly to follow-up questions. Tell your adviser about any deadlines in a purchase agreement.
Understand conditional pre-approval
If you have not chosen a home, conditional pre-approval can guide your search. It is not final approval for every property. The lender normally needs to assess the chosen property before confirming finance.
If the answer is not what you expected
Ask what affected the decision. Next steps could include changing the purchase budget, reducing debt, providing more evidence or considering another suitable lender. Avoid making several applications without first understanding the issue.
Approval
Check the conditions and the property
Read the written approval
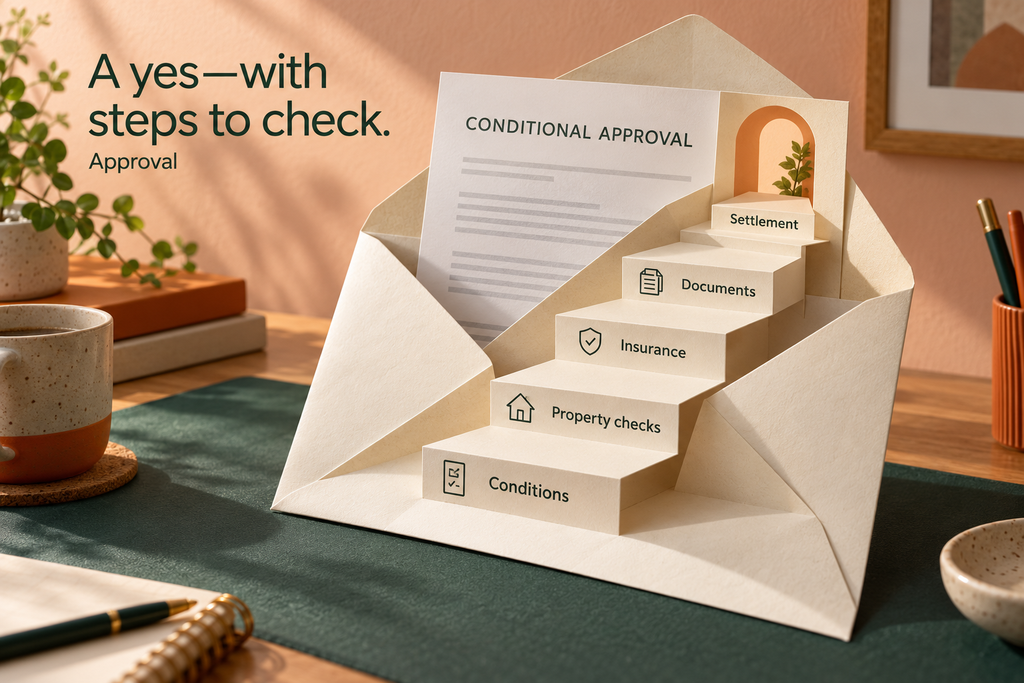
Do not rely only on a verbal update or the word “approved”. Confirm the borrowing limit, expiry date, property restrictions, valuation requirements, debts to repay, documents outstanding and changes to report. If approval expires, ask about renewal and any updated assessment.
Complete property checks
Discuss the title and restrictions, LIM and council records, building inspection findings, insurance availability, unit-title body corporate information and any required valuation. A valuation and a building inspection serve different purposes.
Confirm finance before going unconditional
A conditional agreement may allow time for specified checks, including finance. Have your lawyer advise on wording and deadlines. Confirm the necessary finance before removing the finance condition.
Buying at auction? A successful purchase is generally unconditional. Obtain legal advice and property-specific finance confirmation before bidding.
Understand the two deposit amounts
Your overall deposit contribution is the portion of the price funded without the home loan. The sale and purchase deposit is the amount payable under the agreement at the agreed time.
A buyer contributing $140,000 overall may pay part of that earlier as the contractual deposit. Confirm with your lawyer when funds are needed and whether planned sources, including KiwiSaver, can meet that deadline.
Choose your loan structure
Discuss fixed or floating rates, split loans, total term, repayment frequency, extra repayment rules, offset or revolving credit features where suitable, fees and cashback conditions. Choose around your income, budget and financial habits.
Report changes before settlement
Tell your adviser or lender about significant changes such as new borrowing, a job change, reduced income or a smaller deposit. Do not assume that approval means later changes have no effect.
Settlement
Prepare for the handover
Complete documents early
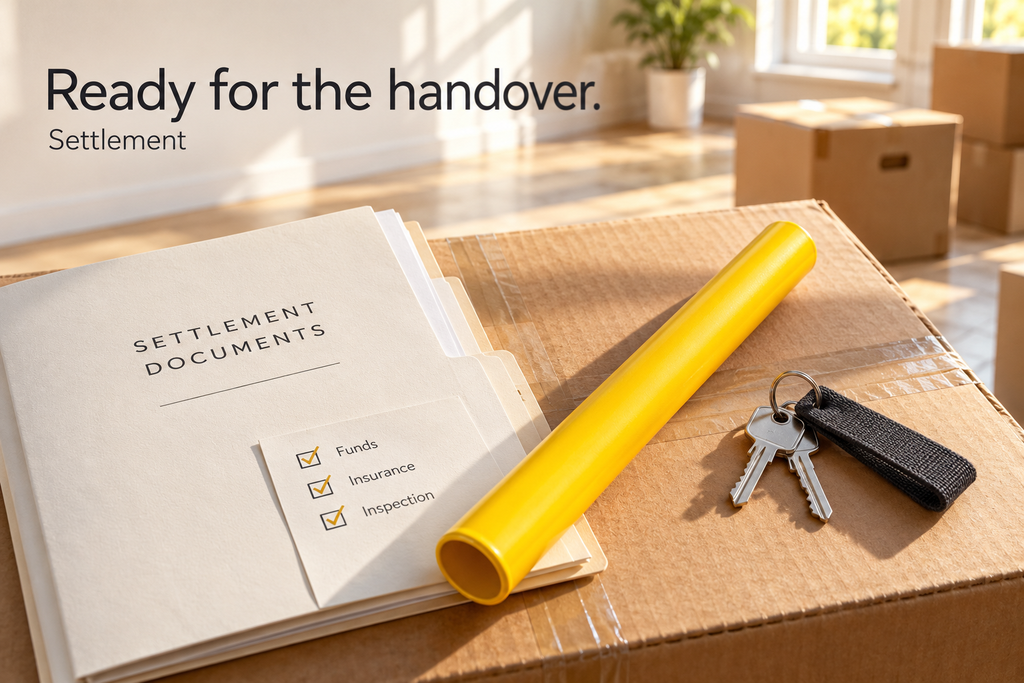
Allow time to review and sign loan and legal documents. Ask your lawyer to explain anything unclear and confirm required identity checks are complete.
Confirm the money required
Your lawyer should explain your contribution, adjustments and costs. Keep funds accessible and allow processing time. Independently verify payment instructions using a trusted phone number before transferring a large amount.
Follow up KiwiSaver arrangements
Confirm progress with your provider and lawyer. Allow the provider’s required processing time rather than leaving the withdrawal until the last few days.
Arrange insurance
Check when cover must start and what the lender requires. Confirm the property can be insured on acceptable terms before committing to purchase.
Complete the pre-settlement inspection
Arrange access through the agent. Check the property and included chattels against the agreement. Tell your lawyer about concerns promptly; do not assume you can deduct money or delay payment yourself.
Wait for confirmation
Your lawyer coordinates completion and funds transfer. Collect keys once settlement and release are confirmed. Keep moving arrangements flexible because the completion time can vary.
Check the first repayment
- Confirm the first repayment amount and date.
- Check the payment account and automatic payment or direct debit arrangements.
- Know where to view loan statements.
- Record your fixed-rate expiry and review date.
- Continue building an emergency and maintenance fund.
Your goal at this stage
Settlement complete, clear repayment arrangements and a practical plan for managing your home.WATCH OUT FOR
Common mistakes to avoid
- Saving for the deposit but forgetting buying costs.
- Assuming pre-approval is final approval.
- Taking on new debt without checking its effect.
- Leaving documents or KiwiSaver arrangements until the last minute.
- Treating the maximum loan amount as a spending target.
- Signing or bidding before appropriate legal and finance advice.
- Hiding debts or submitting incomplete information.
- Using the emergency buffer for furniture immediately after buying.
YOUR ACTION PLAN
Your mortgage readiness checklist
Tick items as you go.
1.Progress is saved in this browser where supported.
2.Set a realistic buying goal and savings target.
3.Review income, spending, debts and credit limits.
4.Check credit reports and request any corrections.
5. Confirm deposit sources and Kiwi Saver eligibility.
6.Budget for buying costs and keep an emergency buffer.
7. Discuss your circumstances with a mortgage adviser.
8.Gather complete documents requested by the lender.
9. Arrange a lawyer or conveyancer before offering.
10. Understand pre-approval conditions and expiry.
11.Complete property checks and confirm finance.
12.Review the loan structure, fees and repayment rules.
13.Report material changes before settlement.
14.Arrange documents, funds, insurance and inspection.
15.Confirm settlement, key release and first repayment.
You don’t need everything ready to ask for guidance.
Talk to Mortgage Advisors about your starting point, practical next steps and a realistic application plan.

