
Pre-approval is an important step toward buying a home — but it does not stay current forever. Here is what to know while you are house hunting.
You have your mortgage pre-approval and you are ready to start looking for a home. But what if the right property does not appear straight away?
Mortgage pre-approval is generally issued for a limited period. The exact validity period depends on the lender and the approval you receive, so the most important date is the expiry date stated on your own pre-approval.
Pre-approved today does not automatically mean pre-approved months from now.
Why does mortgage pre-approval expire?
A lender assesses your application using the information available at that time. Over the following weeks or months, your financial circumstances can change — and so can lender policies, servicing assumptions and lending requirements.
An expiry date gives the lender an opportunity to confirm that the information supporting the original decision is still current before relying on it again.
What can change while you are house hunting?
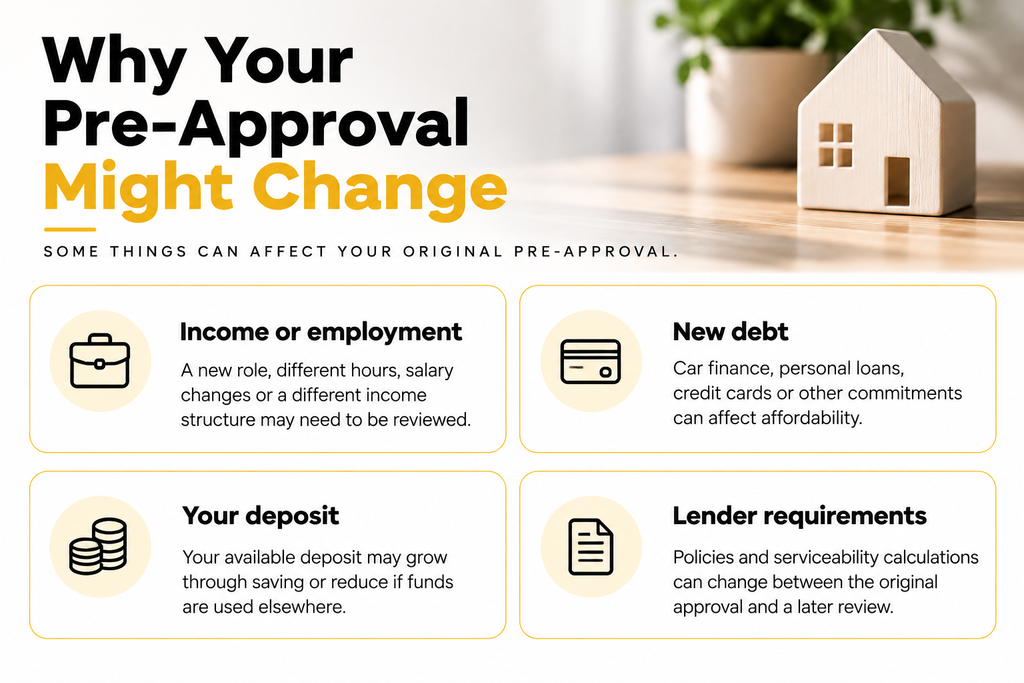
Even when your home-buying goal stays the same, the financial picture behind your application may not. A change in income, employment, savings, expenses or debt can affect how a lender views your application.
What happens if your pre-approval is about to expire?
If you are still actively looking for a home, speak with your mortgage adviser before the expiry date. Depending on the lender and how much time has passed, updated information may be required to review, renew or reassess the application.
This can include recent payslips, bank statements, updated savings or deposit evidence, current debt information and confirmation of your expenses or employment.
Can your borrowing amount change?
Yes. A previous pre-approved amount should not automatically be treated as your current borrowing capacity. If your circumstances or the lender’s assessment settings have changed, the amount a lender is prepared to consider may also change.
Changes can work in either direction. Paying down debt, increasing savings or receiving a sustainable increase in income may strengthen your position, while taking on new commitments can reduce available borrowing capacity.
Do you need to start the whole application again?
Not always. What is required depends on the lender, the age of the original application and whether anything material has changed. Your mortgage adviser can check what needs refreshing and help organise the updated information.
What should you avoid after getting pre-approval?
You do not need to put your life on hold, but it is sensible to understand the possible effect of major financial decisions while you are preparing to buy. Before taking on a new car loan, personal loan, large credit facility or another significant commitment, consider speaking with your mortgage adviser.
Pre-approval is not full mortgage approval
Pre-approval generally relates to your borrowing position subject to the lender’s conditions. Once you find a property, the lender may still need to assess that particular property and complete any remaining checks before the lending can progress to full approval.
That is why an active pre-approval is useful for house hunting, but it should not be treated as guaranteed finance for every property.
How to keep your pre-approval journey on track
Keep an eye on the expiry date, keep your mortgage adviser informed of meaningful financial changes, and avoid assuming that an older approval still reflects your current position.
If you have been searching for a while, a review before you make an offer can give you a clearer picture of where things stand.
Frequently Asked Questions
1. Does mortgage pre-approval expire?
Generally, yes. Pre-approvals are usually issued for a limited period. Check the expiry date and conditions on the approval provided by your lender.
2.Can mortgage pre-approval be renewed?
Depending on the lender and your circumstances, the application may be reviewed, renewed or reassessed. Updated information may be required.
3.Can my borrowing amount change when it is reviewed?
Yes. Changes to income, expenses, debt, deposit, lender policy or servicing calculations can affect the amount a lender is prepared to consider.
4.What if I take out a car loan after pre-approval?
A new repayment commitment can affect affordability. It is sensible to discuss significant new borrowing with your mortgage adviser while preparing to buy a home.
5.Should I make an unconditional offer because I have pre-approval?
Pre-approval should not automatically be treated as full approval for a particular property. Check the lending position and obtain appropriate legal advice before making an unconditional commitment.
Still searching for the right home?
If your pre-approval expiry date is getting closer, Mortgage Advisors can help review your position and guide you through the next step


