
A mortgage decline can be frustrating, but understanding the reason behind it can help you work out what to do next.
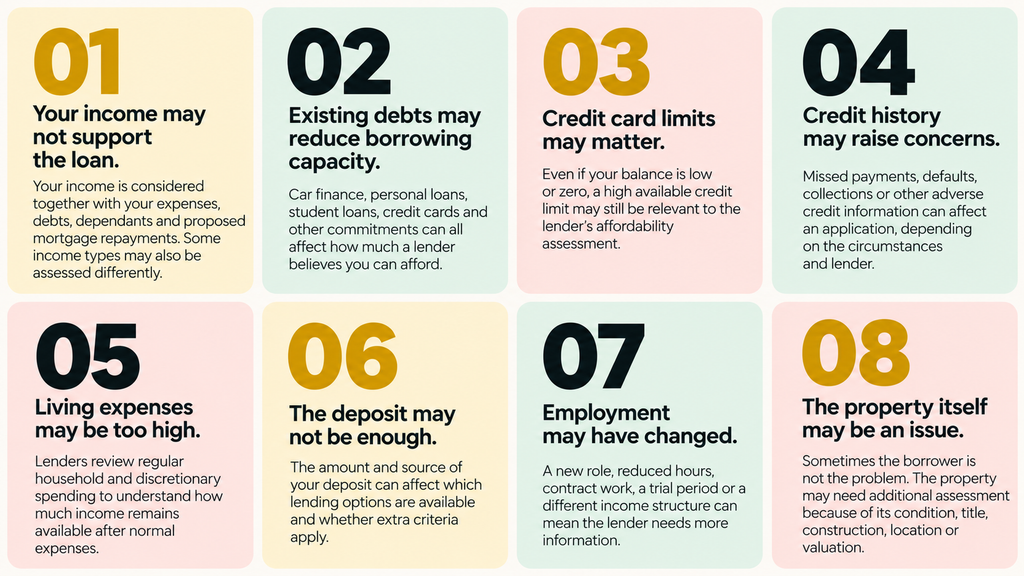
When you apply for a home loan, lenders assess much more than just your income. They look at your overall financial position, your existing commitments, your credit history, your deposit, the property you want to buy and whether the application fits their lending criteria.
A decline does not always mean that home ownership is out of reach. Sometimes the application simply does not fit a particular lender’s policy, or there may be an area of the application that needs attention before you try again.
One lender’s answer may not be the final answer. The important part is understanding why.
Why Do Mortgage Applications Get Declined?
A mortgage application may be declined when the lender is not satisfied that the application meets its lending requirements. Different lenders can assess the same situation differently, so it is useful to understand the exact reason before deciding on the next step.
Existing Financial Commitments Can Carry More Weight Than You Expect
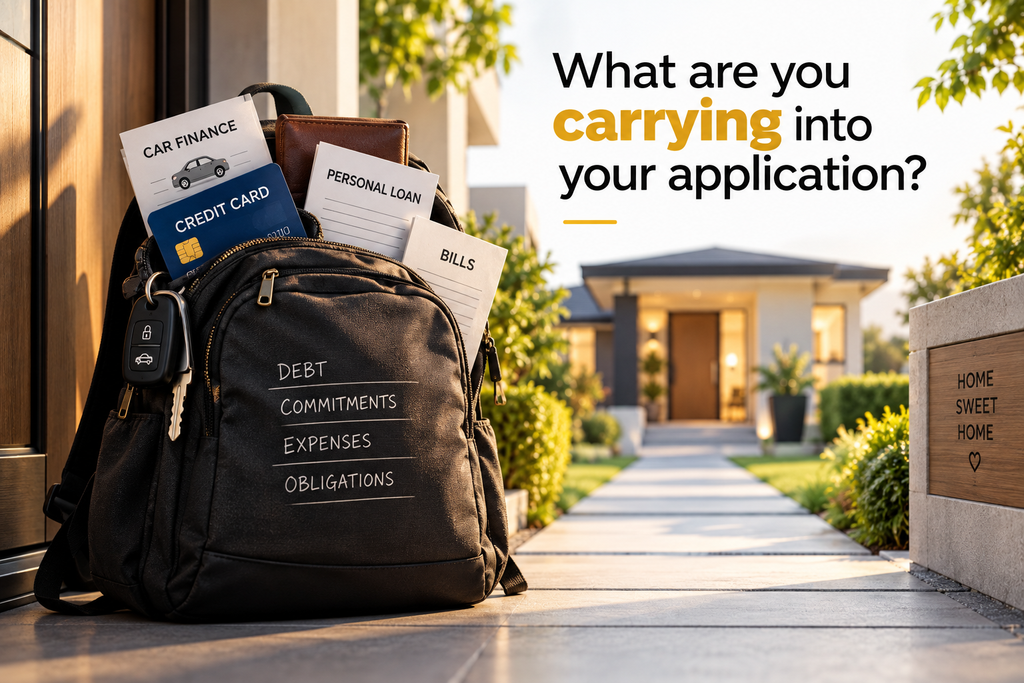
When lenders review your application, they look at the full financial picture. Existing commitments such as car finance, personal loans, credit cards and regular expenses can reduce the amount available for mortgage repayments.
This is why it can be useful to review debts and credit facilities before applying. In some situations, reducing unnecessary limits or clearing smaller commitments may improve the overall application.
What If One Lender Says No?
A decline from one lender does not automatically mean every lender will make the same decision. Banks and non-bank lenders can have different policies around income, employment, deposits, credit history, property types and affordability.
However, this does not mean the same application should simply be sent everywhere. It is usually better to first understand the reason for the decline and then decide whether the application needs to be improved or whether another lender may be more suitable.
Lenders Look Beyond Your Income
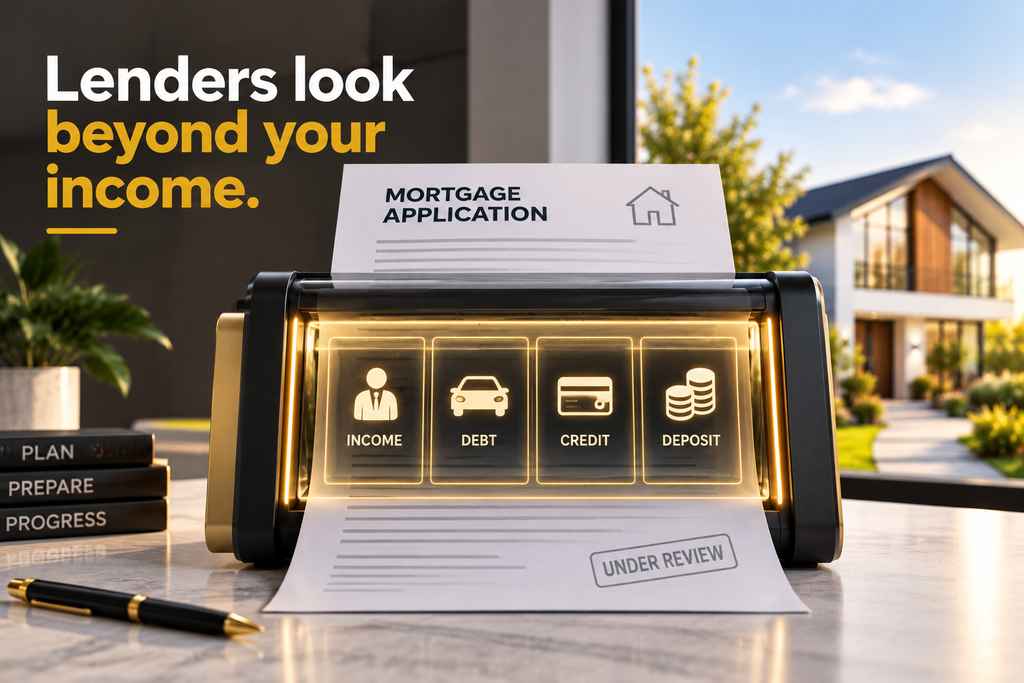
A strong salary is only one part of the assessment. Lenders may also consider:
- Your existing debts and repayment commitments
- Your credit history and available credit limits
- Your deposit and where it came from
- Your living expenses
- Your employment type and income stability
- The property you intend to purchase
- The lender’s current serviceability and lending policy
Can You Apply Again After Being Declined?
Potentially, yes. But the best approach depends on why the application was declined in the first place.
Someone who needs a longer employment history may need a very different strategy from someone whose main issue is high debt or limited deposit. The goal should not simply be to apply again. It should be to make the next application stronger and better suited to your circumstances.
How a Mortgage Adviser Can Help
A mortgage adviser can review your overall financial position before an application is submitted and help identify potential issues. This may include looking at your income, debts, credit facilities, deposit, expenses and intended property purchase.
Where appropriate, an adviser can also compare different lender criteria rather than assuming that one lender is suitable for every borrower.
Frequently Asked Questions
1. Does one mortgage decline mean every lender will decline me?
No. Lenders have different criteria, although it is important to understand the reason for the first decline before another application is considered.
2.Can debt cause a mortgage application to be declined?
Yes. Existing repayments and credit facilities can reduce affordability and borrowing capacity.
3.Can spending habits affect a home loan application?
Yes. Living expenses form part of the lender’s affordability assessment and can influence the outcome.
4.Can bad credit stop me from getting a mortgage?
Adverse credit can affect an application, but the outcome depends on the type of issue, when it occurred, your current position and the lender’s criteria.
5.Can a mortgage be declined after pre-approval?
Yes. Pre-approval is generally conditional, and changes to your finances, the property or lender requirements can affect the final decision.
Mortgage application declined?
Before making another application, understand what caused the decline and what options may be available from here.


