

Buying your first rental property starts with more than finding a house and applying for a loan. You need to understand how the mortgage will work, what the property could cost to hold and whether your finances can support it through quieter periods.
This beginner’s guide to investment property mortgages explains the process in New Zealand, from preparing your deposit to settlement and your first year as a landlord. Whether you already own a home or are considering a rental as your first purchase, start with borrowing you can sustain.
What Is an Investment Property Mortgage?
An investment property mortgage finances a property you intend to rent out rather than primarily live in. The lender assesses your finances and the property offered as security, including its intended use and potential rental income.
Investor lending can have different deposit requirements and assessment criteria from owner-occupied lending. Tell your broker how you intend to use the property from the start. Buying a rental as your first property does not automatically make the application an owner-occupied first-home loan.
1. Are You Financially Ready to Invest?
Review your income, household spending, current mortgage, other debts and savings before looking at listings. Consider whether your employment is stable and whether you expect changes to your income or family commitments.
A rental can require contributions from your own income. Repairs, tenant turnover and interest-rate changes can affect your budget, even when the property is otherwise performing well. Decide how much uncertainty you can comfortably manage.
Keep Money Available for the Unexpected
Set aside accessible savings for vacancies, insurance excesses and maintenance. Your deposit should not leave you unable to handle a broken hot-water cylinder or several weeks without rent. The appropriate buffer depends on your property, commitments and income stability.
2. How Much Can You Afford?
Your borrowing capacity depends on more than the deposit. Lenders consider income, spending, debt commitments and their repayment assessment criteria. They may use a higher assessment interest rate than the rate you would initially pay.
Expected rent can support an application, but lenders commonly count only part of it when assessing repayment ability. Ask how your chosen lender treats rental income and what evidence it requires. A rental appraisal is an estimate, not guaranteed receipts.
Build a Holding-Cost Budget
Include mortgage payments, council rates, insurance, maintenance, management fees, body corporate charges where applicable and a vacancy allowance. Work out the expected shortfall before making an offer.
For illustration, $650 weekly rent provides $33,800 annually at full occupancy. If mortgage payments and other cash outgoings total $38,000, you would need to contribute $4,200 before tax. Unexpected costs or vacancies would increase that gap. These figures are hypothetical, not a rental or lending forecast.
3. Saving for the Deposit or Using Equity
Your contribution may come from savings, sale proceeds, an acceptable gift or additional borrowing secured against an existing property. Tell the lender where the money comes from and disclose any repayment obligation.
Using home equity usually means borrowing more. If the deposit is borrowed against your home, include that loan alongside the investment mortgage in your budget. Equity is not a substitute for income or a guarantee of approval.
Keep purchase expenses separate from the deposit calculation. Legal advice, inspections, valuation fees and any initial repairs can require additional cash before rental income begins
4. Understanding Loan-to-Value Ratio (LVR)
LVR compares borrowing with the lender-accepted value of the property securing it. A $490,000 loan against a $700,000 property has a 70% LVR. The remaining $210,000 represents a 30% contribution in this simplified single-property example.
Under current Reserve Bank settings, investor lending above 70% LVR is classified as high-LVR. Banks may allocate no more than 10% of their new investor lending to that category. This is a bank lending restriction, not an absolute rule that every investor must provide a 30% cash deposit.
Exemptions and combined-security arrangements may affect a transaction. However, banks still apply their own policies and can require a larger contribution. Check the rules and available options when applying rather than assuming access to a high-LVR loan.
5. Understanding Debt-to-Income Ratio (DTI)
DTI compares total debt, including proposed borrowing, with annual gross income recognised for the calculation. For example, total debt of $840,000 divided by recognised annual income of $140,000 gives a DTI of six.
Current Reserve Bank rules allow banks to allocate up to 20% of investor lending to borrowers with a DTI above seven. This is a speed limit on bank lending, not a promise that you can borrow seven times your income.
Existing mortgages and other debts affect the calculation. Lenders also carry out separate affordability checks, so meeting the DTI threshold does not mean repayments are affordable or the loan will be approved. Ask your broker how rental income and credit facilities affect your application.
6. Improving Your Financial Position
Before applying, consider reducing expensive debt, reviewing unnecessary credit limits and building a consistent savings record. Make payments on time and check your credit record for errors. Provide accurate information about household expenses.
Self-employed applicants should prepare the financial information the lender requests, which may include accounts and tax records. Explain variable income clearly rather than relying on a strong recent month. A broker can identify evidence gaps before submitting the application.
Avoid taking on new finance during the purchasing process without discussing it with your broker. A new vehicle loan or reduced income can change the lender’s assessment before settlement.
7. Getting Investment Mortgage Pre-Approval
Pre-approval gives an indication of what a lender may offer, subject to its stated conditions. It can help you set a search budget, but it does not automatically approve every property within that budget.
You may need identification, income evidence, bank statements, details of existing lending and proof of your deposit source. The lender can require further property information and an acceptable rental appraisal once you identify a purchase.
Read the expiry date and conditions carefully. Ask whether your finances have been fully assessed, what remains outstanding and what changes could affect the approval.
Related guides: What Is Pre-Approval and Why Is It Important?; Pre-Approval vs Full Mortgage Approval.
8. Choosing a Mortgage Broker
Look for someone who can explain investment lending, rental-income assessment and security arrangements in plain language. Ask which lenders they work with, what fees you might pay and how they are remunerated.
A useful broker should explain the reasoning behind a recommendation, not simply quote an interest rate. Discuss repayment options, future rate changes and what could happen if you sell or refinance one property.
Your broker handles lending advice within their service. Your solicitor and accountant address legal and tax questions. Bringing them into the process early can help you avoid decisions that are difficult to change later.
9. Finding an Investment Property
Choose a property against a clear budget and rental strategy. Research comparable rentals, local demand, access to employment and transport, and the type of home tenants are seeking.
Review condition, maintenance requirements, insurance availability and relevant council information. Apartments and units can involve body corporate obligations and potential major works. A cheaper purchase price does not necessarily mean lower ownership costs.
Check Healthy Homes compliance and other landlord obligations before assuming the property is ready to rent. Obtain advice about existing tenants and tenancy terms if you are buying an occupied rental.
10. Making an Offer and Reviewing the Agreement
Have your solicitor review the sale and purchase agreement before signing. Discuss suitable conditions for finance, building checks, council information and other due diligence, with realistic deadlines.
The agreement records more than the price. Settlement timing, included chattels, deposit payment and existing tenancy arrangements can all affect the purchase. Clarify whether the property will be vacant or tenanted at settlement.
The contractual deposit paid under the agreement is different from your total contribution for mortgage purposes. At auction, purchases are generally unconditional, so arrange legal, property and lending checks before bidding. Do not treat pre-approval as sufficient on its own.
11. Building Inspections and Valuation
A building inspection helps identify condition issues and potential maintenance costs. A lender-required valuation estimates value for lending purposes. Neither replaces legal review of the title or council information.
Use suitably qualified professionals and ask about the scope and limitations of their reports. If a lender requires a registered valuation, follow its approved ordering process.
A valuation below the purchase price can affect your LVR and required contribution. Discuss that risk before committing unconditionally, particularly where your deposit has little room for adjustment.
12. Choosing Your Mortgage Structure
Fixed, Floating or Split Lending
Fixed-rate portions provide interest-rate certainty for an agreed period. Floating portions can offer flexibility, but rates can change. Splitting a loan may combine these features or spread fixed-term expiry dates.
Consider extra-repayment limits, early-repayment costs and your plans for the property. A lower initial rate may not provide the flexibility you need if you intend to renovate, sell or reduce borrowing quickly.
Principal-and-Interest or Interest-Only
Principal-and-interest repayments reduce the debt over time. Interest-only repayments do not reduce principal during the approved period and may rise when principal repayments begin.
If considering interest-only lending, compare long-term costs and plan for the end of the period. Keep personal and investment borrowing clearly documented and discuss tax treatment with your accountant.
Related guide: How to Choose the Right Mortgage Structure.
13. Final Mortgage Approval and Settlement
Once a property is selected, the lender reviews the required information and confirms its conditions. Your broker should explain what still needs to be supplied before lending can be drawn down.
Before declaring a finance condition satisfied, obtain advice from your broker and solicitor about the written approval and outstanding requirements. Confirm suitable insurance, review loan documents and understand repayments, security and fees.
Your solicitor coordinates the legal settlement process and transfer of funds. Arrange any remaining contribution by the required time. Coordinate keys, property management and existing tenancy information so ownership begins with a clear handover.
14. Your First 12 Months as a Landlord
Instead of moving in, your next step is managing the rental. Decide whether you will self-manage or appoint a property manager, and understand tenancy agreements, bond handling, inspections and repair responsibilities.
Track actual rental receipts and expenses against your original budget. Rebuild your cash buffer after unexpected costs and plan for fixed-rate expiry dates before they arrive.
From 1 April 2025, qualifying residential rental interest can be fully deductible, subject to general deductibility rules. A deduction does not refund the full interest cost. Ask your accountant about records, rental loss restrictions and potential sale tax; do not assume a rental shortfall can offset salary income.
Common Beginner Investment Mortgage Mistakes
Frequent mistakes include spending the entire cash reserve on the deposit, assuming rent will cover every expense and confusing accessible borrowing with total equity. Another is choosing interest-only repayments without planning for the later increase.
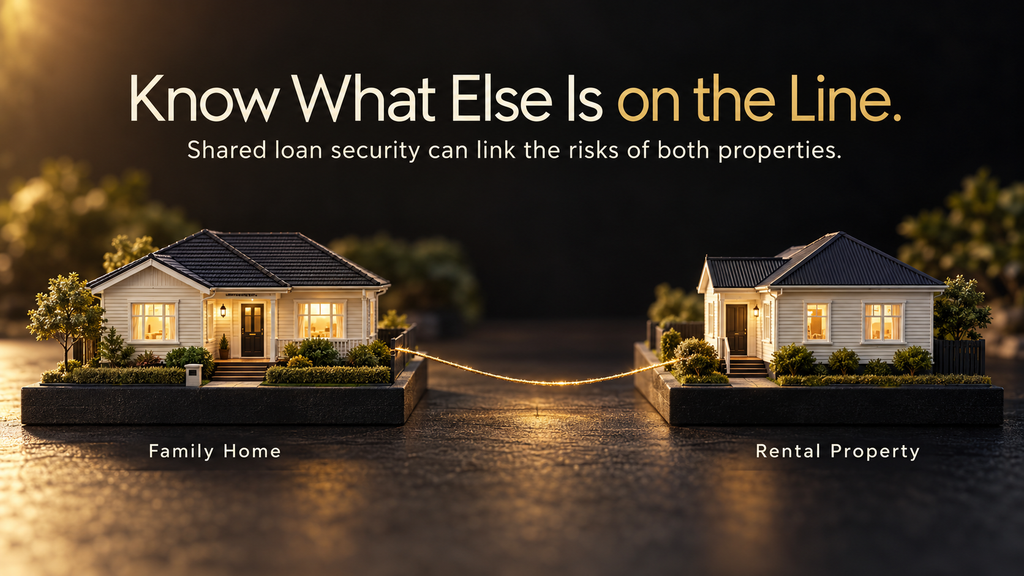
Other avoidable problems include signing unconditionally too early, overlooking security over the family home and budgeting around guaranteed price growth. A property must be manageable while you own it, even if future resale proceeds disappoint.
Frequently Asked Questions
Can my first property be an investment property?
Yes, subject to lender approval and any eligibility restrictions. Explain the intended rental use clearly. First-home assistance generally has occupancy conditions, so do not assume it can fund a rental purchase.
Do I always need a 30% deposit?
No universal cash-deposit rule applies to every transaction. A 70% LVR is an important investor threshold, but exemptions, security arrangements and lender policies matter. Ask what contribution is required for your specific purchase.
Can I use equity in my home?
Potentially, with approval and sufficient repayment capacity. Additional borrowing increases your commitments and may put your home at risk if it secures the investment debt.
Will the lender count all the rent?
Not necessarily. Lenders commonly make an allowance for rental costs and interruptions. Ask what income will be recognised and what evidence is needed.
Does pre-approval mean I can buy any property?
No. The lender must accept the property and all relevant conditions must be met. Obtain property-specific lending advice before making an unconditional commitment.
Beginner Investment Property Checklist
✓ Review income, spending, debts and cash reserves.
✓ Confirm the deposit source and purchase expenses.
✓ Discuss LVR, DTI and repayment affordability.
✓ Obtain pre-approval and understand its conditions.
✓ Research rental demand and complete property checks.
✓ Have your solicitor review the agreement before signing.
✓ Confirm valuation, insurance and final finance requirements.
✓ Choose a loan structure and understand the security.
✓ Arrange settlement and rental management.
✓ Track cash flow, maintenance and mortgage review dates.
Speak With a Mortgage Broker
Considering your first rental property? Talk to Mortgage Advisors about your borrowing capacity, deposit or equity options and potential loan structures. Bring details of your income, debts, savings and property plans so the discussion starts with your actual financial position.

