

Property can help you build long-term wealth, but owning a house is only the beginning. The real work is choosing an affordable property, managing the borrowing and keeping enough money available to handle the unexpected.
If you are wondering how to build wealth through property in New Zealand, start with a plan rather than a price prediction. A property investment needs to fit your income, financial commitments and goals, even when interest rates change or the property sits empty.
This guide explains how equity, rental income and mortgage repayments work together, what to check before buying, and how a mortgage broker can help you assess the lending side of your next step.
What Does Building Wealth Through Property Mean?
Building wealth means increasing what you own after subtracting what you owe. With property, that involves looking beyond the purchase price to the mortgage balance, running costs and money you have contributed over time.
A property worth $800,000 with a $600,000 mortgage has $200,000 in equity before selling costs. That equity forms part of your net worth, but it is not the same as $200,000 available in your bank account.
Your own home can contribute to wealth through mortgage reduction and possible value growth. A rental property adds another potential source of returns: rent. However, neither ownership nor rental income guarantees a profit.
1. Understand the Three Main Ways Property Can Build Wealth
Capital growth
Capital growth happens when a property increases in value. Location, housing demand, condition and wider economic conditions can all influence prices. Values can also fall, so avoid building your entire plan around an assumed annual increase.
A higher valuation does not create spendable cash by itself. You usually need to sell or obtain additional approved borrowing to access it, and both options can involve costs.
Rental income
Rent can help cover the costs of an investment property. What matters is how much remains after expenses, financing and tax, rather than the weekly rent alone. A high rent can still leave you needing to contribute money each month.
Mortgage principal reduction
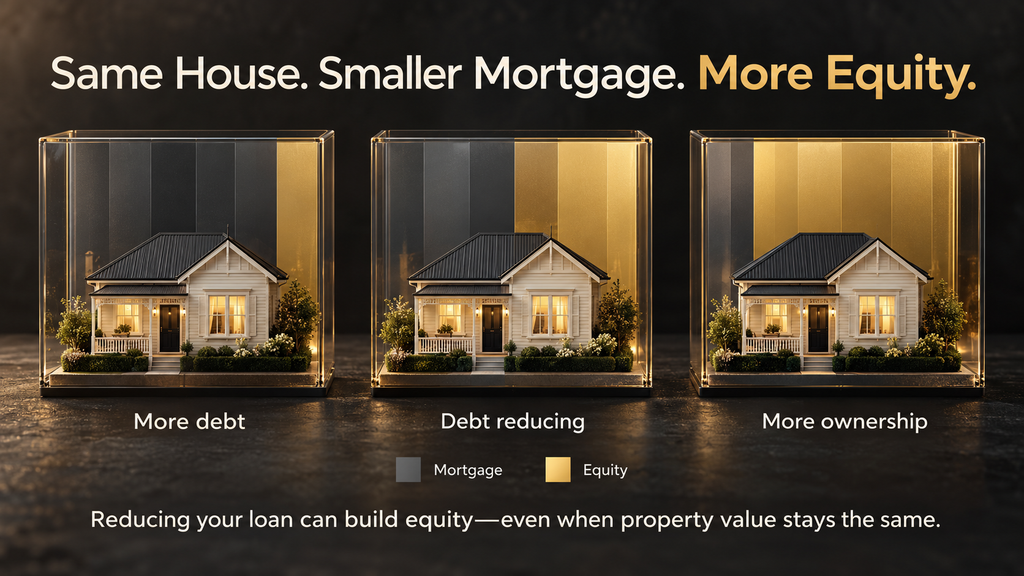
Principal-and-interest repayments gradually reduce your loan balance. If the property value stays the same, reducing the mortgage increases your equity. This can provide progress without relying on rising house prices.
Remember that principal repayments come from your money or rental receipts. Increasing equity through repayment is different from earning an investment profit, although both can improve your financial position.
2. Start With Your Financial Position
Before browsing listings, work out what you can comfortably support. Review your income, everyday spending, existing mortgage, other debts and savings. Allow for family expenses and any changes you already expect, such as reduced working hours.
A lender’s maximum loan offer should not automatically become your purchasing budget. Your personal comfort level may be lower, especially if you want room for travel, children, retirement savings or business commitments.
Keep a cash buffer
Property can require money at inconvenient times. An insurance excess, urgent plumbing repair or gap between tenants can arrive while your usual household bills continue. Keep accessible savings rather than committing every available dollar to the deposit.
The right buffer depends on your income stability, property condition and other commitments. Estimate several realistic disruptions and work out how long you could manage them without taking on expensive debt.
Related guide: How Much Should You Keep in an Emergency Fund Before Buying a Home?
3. Choose a Property That Fits Your Strategy
Before deciding where to buy, decide what you need the property to do. Are you prioritising manageable holding costs, potential long-term value growth or an opportunity to improve an existing home? Those goals can lead to different choices.
Look at demand and practical costs
Research comparable rentals and recent sales. Consider access to jobs, transport, schools and everyday services, alongside the property type tenants in that area want. A rental appraisal can help, but treat it as an estimate rather than guaranteed income.
Check building condition, title restrictions, council information, insurance availability and exposure to flooding or other hazards. For an apartment or unit, review body corporate fees, records and potential major works with suitable professional help.
In New Zealand, private rentals must comply with the Healthy Homes standards unless an applicable exemption applies. Budget for compliance checks and required work before relying on the property’s rental potential.
4. Run the Numbers Beyond Weekly Rent
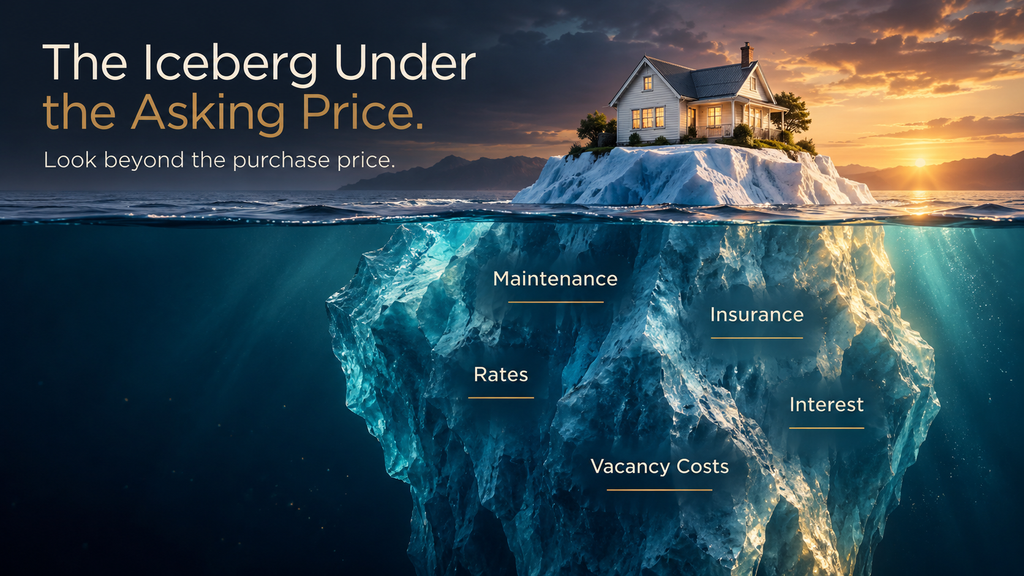
Compare expected rental receipts with the full cost of ownership. Include rates, insurance, maintenance, management fees, vacancy allowances, body corporate charges where relevant and mortgage payments. Legal, valuation and inspection costs also affect your initial investment.
Gross yield is only a starting point
Gross rental yield is annual rent divided by the purchase price, multiplied by 100. It helps compare properties, but excludes operating expenses, financing, vacancy and tax. A property with a higher gross yield is not automatically the better investment.
Purchase price: $700,000
Rent: $650 per week
Annual rent at full occupancy: $33,800
Gross rental yield: approximately 4.83%
Assume a $490,000 loan at an illustrative 6% interest rate on interest-only terms. Annual interest would be $29,400. If operating costs and allowances total $8,000, the annual cash shortfall would be $3,600 before tax.
Principal repayments, purchase costs and additional borrowing for the deposit are excluded. These assumptions are not a current rate quote, rental forecast or lending offer.
This example shows why rent alone does not tell the whole story. If the loan required principal repayments, cash outgoings would be higher, although some money would reduce debt. If rent stopped for several weeks, the shortfall could increase further.
Stress-test your budget
Calculate what happens with a higher interest rate, lower rent, several empty weeks and an unexpected repair. Test some events together. A workable investment should have a funding plan for difficult periods, rather than depend entirely on ideal conditions.
5. Use Equity Carefully
Existing homeowners may be able to use some equity to support another purchase. However, total equity and lender-approved borrowing capacity are different things. The lender also considers income, expenses, existing debts, acceptable security and its lending policies.
Equity example
Home value: $900,000
Mortgage balance: $500,000
Total equity: $400,000 If a lender hypothetically permitted total lending up to 80% of that home’s value, the difference would be $220,000. This is a simplified illustration, not an entitlement to borrow. Approval and actual limits depend on your circumstances and the proposed lending.
orrowing against equity creates additional debt. If you borrow the deposit as well as the investment mortgage, include repayments on both loans in your assessment. The deposit is not free money simply because it comes from your existing home.
Ask which properties secure which loans and what happens if you sell one. Where your family home supports investment borrowing, repayment problems can put that home at risk. Understand the security arrangements before proceeding.
6. Choose a Mortgage Structure That Supports Your Plan
The way your lending is organised can affect budgeting and flexibility. Fixed portions offer rate certainty for an agreed period, while floating or other flexible portions may suit planned extra repayments. Product features and costs vary between lenders.
Principal-and-interest versus interest-only
Principal-and-interest repayments reduce debt over time. Interest-only lending may reduce scheduled payments during an approved period, but the balance does not fall through those payments. Repayments can increase when principal repayment begins.
Interest-only terms should therefore come with a clear reason and an exit plan. Compare the long-term costs and future repayment requirements, rather than choosing solely on the lowest initial payment.
Keep loan purposes clear
Discuss separating personal and investment borrowing with your broker and accountant. Clear records can help identify what borrowed funds were used for. The property offered as security does not, by itself, determine whether interest is deductible.
7. Improve the Property With a Clear Budget
Well-planned improvements may make a property more appealing to tenants or buyers. Focus first on necessary repairs, compliance and practical features. A dry, comfortable, functional home can be more useful than expensive finishes that do not suit the local market.
Get quotes, check consent requirements and allow for delays and unexpected costs. Compare the complete project cost with a realistic potential benefit. A $30,000 renovation does not automatically increase the valuation by $30,000 or produce a matching rent increase.
If you need to borrow for improvements, include the extra financing costs. Avoid treating renovation as a guaranteed shortcut to equity, especially when the project depends on optimistic resale estimates.
8. Understand Tax and Ownership Responsibilities
Tax affects your actual return, so speak with an accountant before buying or changing how a property is used. Rental income, deductible expenses, ownership arrangements and a future sale may all have tax consequences.
From 1 April 2025, 100% of qualifying residential rental interest can be deductible, subject to the general deductibility rules. That is a deduction against taxable income, not a refund of the full interest cost.
For sales on or after 1 July 2024, the bright-line test generally considers whether the relevant end date falls within two years of the start date. Other land-sale tax rules can still apply outside that period. Do not assume a sale becomes tax-free simply after two years.
Ask how rental loss restrictions affect your position; do not assume a rental shortfall will reduce tax on your salary. Keep records of income, expenses and borrowing, and allow for landlord obligations, insurance and ongoing maintenance.
9. Grow at a Pace You Can Sustain
Buying more properties increases both your assets and your commitments. Before another purchase, review the performance of what you already own. Check whether your buffer has recovered and whether your income can support the additional exposure.
Consider concentration risk too. Several rentals in one location can all be affected by the same local downturn or hazard. Property also takes time and money to sell, so consider how it fits alongside accessible savings and other investments.
Review Your Property Strategy Over Time
Revisit your plan when fixed rates expire, your household income changes or major maintenance is approaching. Compare actual costs with your original estimates and update your cash-flow assumptions using current information.
Success does not have to mean buying another property every year. Reducing debt, strengthening your buffer or keeping one well-managed investment may be the next step that best supports your goals.
Frequently Asked Questions
Can I build wealth through my own home?
Yes, mortgage reduction and possible value growth can increase equity. However, your home generally does not produce rental income, and ownership costs still matter. Equity is also less accessible than cash savings.
How much deposit do I need for an investment property?
It depends on the lender, property and lending rules applicable to the transaction. Your broker can assess potential options. Include purchase costs and a cash buffer alongside the deposit.
Can I use home equity to buy a rental?
Potentially, subject to lender approval and affordability. Using equity normally involves additional borrowing. Include all related repayments and understand any risk to your existing home.
Does rent need to cover the entire mortgage?
A property can have a cash shortfall, but you need a sustainable way to fund it. Assess operating costs, mortgage payments and tax together. Future capital growth may not offset losses.
Is an interest-only mortgage better for property investment?
It depends on your goals and finances. It can reduce initial payments, but does not reduce principal during that period. Compare future repayments and total costs before deciding.
How long does it take to build wealth through property?
There is no guaranteed timeline. Results depend on purchase costs, borrowing, repayments, rental performance, maintenance, tax and market movements. Plan for a holding period you can afford.
Talk to Mortgage Advisors
Thinking about your first investment property or using existing equity? Speak with a Mortgage Advisors mortgage broker about your borrowing capacity, potential loan structures and how repayments could fit your budget. Bring details of your income, debts, savings and property plans so the conversation starts with your actual position

