

Compare the interest you could save with the growth you could earn—and choose an approach that fits your household.
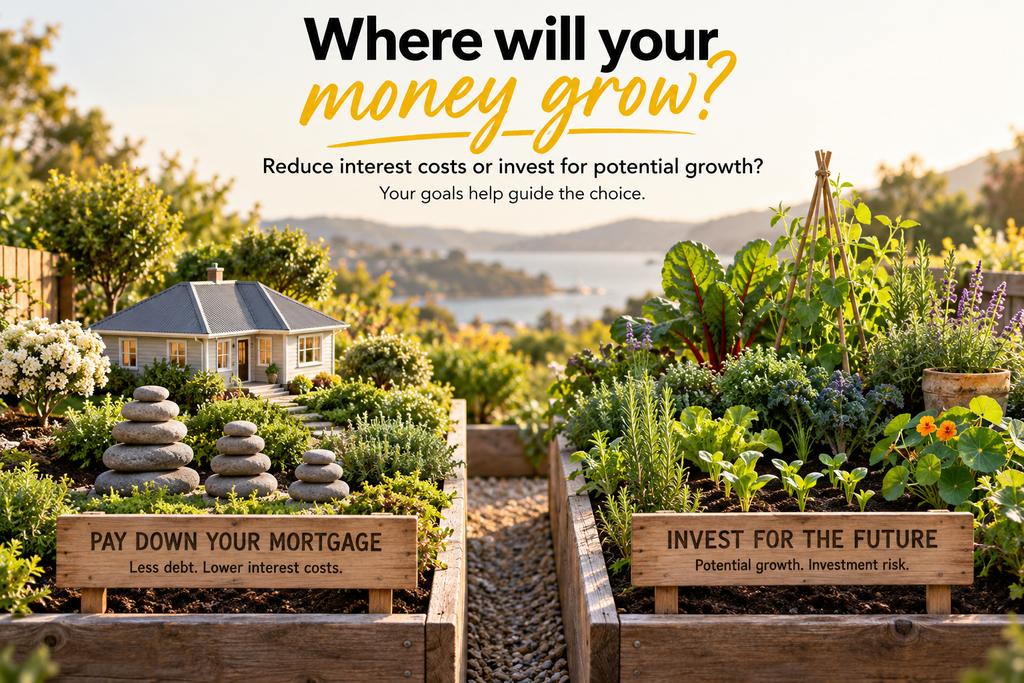
You have some money left after paying the bills. Should you put it towards your home loan, or invest it for the future?
For New Zealand homeowners, both choices can support wealth building. Extra mortgage repayments reduce debt and future interest costs. Investing can help grow assets outside your home, but returns fluctuate and losses are possible.
The better choice depends on your mortgage rate, financial goals, emergency savings and comfort with risk. Some households benefit from focusing on debt reduction. Others can reasonably invest while continuing their scheduled repayments. A combination may suit you too.
If you are deciding whether to invest or pay down your mortgage, start with the money you genuinely have available and compare the options on equal terms.
What Does Paying Down Your Mortgage Achieve?
An extra repayment reduces the principal: the amount you owe. Because mortgage interest is generally calculated on the outstanding balance, reducing that balance lowers future interest charges.
If you keep your regular repayments unchanged, more of each future payment can go towards principal, potentially shortening the loan term. If your lender instead reduces your scheduled payments, the effect on your repayment timeline will be different.
Interest savings are easier to estimate
For a standard owner-occupied mortgage where interest is not tax-deductible, avoiding interest is a useful benchmark for comparing investments. You generally do not pay income tax on interest you avoid paying.
Suppose you repay an extra $10,000 on a mortgage charging 6% a year. If that $10,000 would otherwise remain outstanding throughout the next year and the rate stays unchanged, the approximate first-year interest saving is $600.
This is a simplified illustration, not a current rate quote or repayment forecast. Actual savings depend on repayment timing, daily balances, future rates and any charges. Mortgage repayments also do not generate investment income; their benefit is a reduced borrowing cost.
Lower debt can improve financial resilience
A smaller mortgage can make future income changes or interest rate increases easier to manage. For households approaching retirement, reducing debt may be especially valuable because employment income may soon decline.
There is also a personal benefit. If a large mortgage causes ongoing stress, reducing it can make your finances feel more manageable. That matters even when another strategy has a higher projected return.
What Does Investing Offer?
Investing puts money into assets with the aim of earning income, achieving growth, or both. Depending on your goals, that could include managed funds, shares, bonds or other investments.
The appeal is the opportunity to build wealth beyond your home. However, different investments have different risks, fees, tax treatment and access rules. “Investing” is not one single option with one predictable return.
Long-term growth and compounding
When investment earnings remain invested, future returns can build on earlier gains. Over a long period, this compounding can contribute significantly to growth.
But growth is not smooth. An investment might rise one year and fall the next. A long timeframe gives you more opportunity to ride out market declines, although it does not guarantee a positive result.
Money needed soon for essential expenses generally needs a different approach from money intended for retirement decades away. Choose the timeframe first, then consider suitable investments.
Diversification beyond your property
Your home may already represent most of your wealth. Investing outside property can spread exposure across other assets, industries and countries.
Diversification can reduce dependence on one investment, but it cannot remove all risk. A diversified fund can still lose value, particularly during a broad market downturn.
The objective is to build a portfolio that fits your goals and ability to handle losses, rather than choosing investments simply because recent returns look attractive.
Compare Mortgage Savings With Investment Returns After Costs
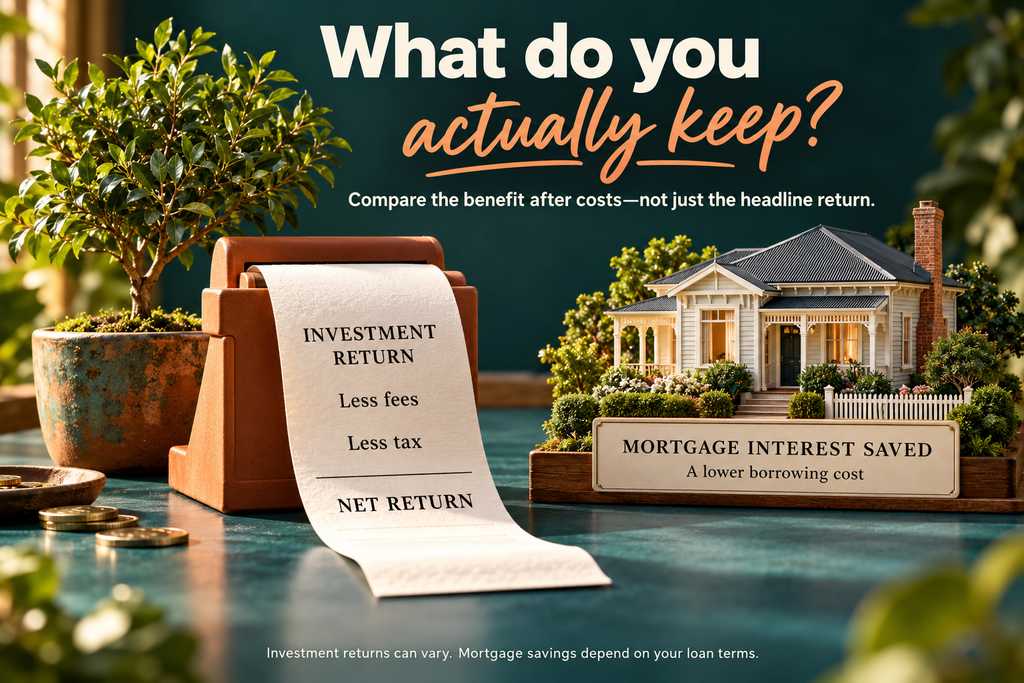
The most useful numerical comparison is between the interest you would avoid and the investment return you might keep after fees and tax.
A headline investment return is not necessarily the return that reaches your pocket. Management fees, transaction costs and tax can reduce the benefit. Investment returns are also uncertain, while mortgage interest savings follow the loan’s actual rate and terms.
A simple worked example
Assume you have $10,000 available, your owner-occupied mortgage rate is 6%, and there is no extra repayment charge.
Putting the money into the mortgage could save approximately $600 in interest over a year under the assumptions described earlier. Now suppose an investment earns 7% before fees and tax. That would be $700 before costs.
If fees and applicable tax reduce that gain by $150, the net gain is $550. In this hypothetical year, the mortgage repayment produces a larger financial benefit. If the investment instead earns 9% and total costs are still $150, its net gain is $750.
Those examples show why the after-cost comparison matters. They do not predict investment performance, and the assumed tax amount is not a calculation for any specific product. An investment could also finish the year below its starting value.
New Zealand tax treatment matters
Tax depends on what you invest in and your circumstances. Income from a multi-rate portfolio investment entity, or PIE, uses a prescribed investor rate. Other investments can have different tax rules.
Do not assume all investment gains are taxed in the same way, or that multiplying a headline return by a single tax rate will always produce the correct answer. Overseas investments can add further complexity.
For investment property borrowing, business borrowing or mixed-purpose loans, interest deductibility can change the comparison. Get tax advice for your situation rather than applying an owner-occupied example to every mortgage.
Build a Financial Buffer Before Committing Surplus Money
Before choosing either strategy, check whether the money is genuinely surplus. Upcoming insurance premiums, school costs, repairs and other predictable expenses need a place in your budget.
An emergency fund helps cover unexpected costs without immediately relying on credit cards, selling investments or seeking another loan. The appropriate amount depends on your essential expenses, income reliability and household responsibilities.
Someone with variable self-employed income may need a different buffer from a household with two stable salaries. Keep emergency money accessible and separate from money allocated to long-term goals.
Also review expensive debt. If a credit card or personal loan charges more interest than your mortgage, repaying that debt may offer a stronger interest saving, subject to its terms.
To find a sustainable amount to allocate each month, read How to Reduce Household Expenses. A realistic budget is more useful than a plan that depends on never having an unexpected bill.
Check Your Mortgage Terms Before Paying Extra
The ability to make extra repayments depends on your lender and loan product. Fixed-rate mortgages may have limits on additional repayments, and exceeding those limits can trigger an early repayment charge.
Ask your lender what you can repay without a charge and request a quote if you are considering a larger lump sum. Compare the cost with the expected interest saving before proceeding.
Your fixed-rate expiry can be a useful review point
When a fixed period ends, you can discuss repayment levels, loan structure and lump-sum payments with your lender or broker. The available options depend on your agreement and lender requirements.
A broker can help you consider whether keeping repayments higher after a rate change could accelerate debt reduction. Avoid assuming that refinancing or restructuring automatically saves money; fees, loan terms and any cashback repayment conditions can affect the result.
Offset and revolving credit options
Some lenders offer offset mortgages that use eligible linked account balances to reduce the balance on which interest is charged. This can allow savings to remain accessible while reducing mortgage interest, subject to product rules.
Revolving credit works differently. It generally provides a borrowing facility within an agreed limit, with interest based on the amount used. Income paid into the facility can reduce borrowing, but spending increases it again.
These products require discipline and may carry different rates or fees from fixed loans. Read How to Choose the Right Mortgage Structure before discussing suitable options with your broker.
When Paying Down Your Mortgage May Be the Better Fit
Debt reduction may suit you if you value predictable interest savings, have a relatively high mortgage rate, or want to reduce financial pressure before retirement.
It can also make sense if investment losses would cause you to abandon your plan. Taking more risk than you can tolerate can lead to poor decisions when markets fall.
However, paying extra into a standard mortgage can reduce access to cash. You may need lender approval to borrow that money again, and approval is not guaranteed. A lower mortgage balance is valuable, but it does not replace accessible emergency savings.
Consider whether extra payments will shorten the term, reduce future required payments, or both. Ask for a repayment projection so you understand the actual effect.
When Investing May Be the Better Fit
Investing may suit homeowners who have a reliable financial buffer, manageable debt, a long timeframe and the ability to tolerate market fluctuations.
It may be attractive when a realistic expected return after costs exceeds the mortgage interest saved by enough to justify the additional risk. A small projected advantage should not be treated as a certain win.
If you contribute to KiwiSaver, consider any employer contributions and government contribution eligibility before changing your approach. These benefits can affect the comparison, while withdrawal restrictions affect access to the money. Check current rules and your circumstances.
An investment adviser can help assess appropriate assets, diversification and risk. Your mortgage broker can explain the home loan side, but investment advice should come from someone qualified and authorised to provide it.
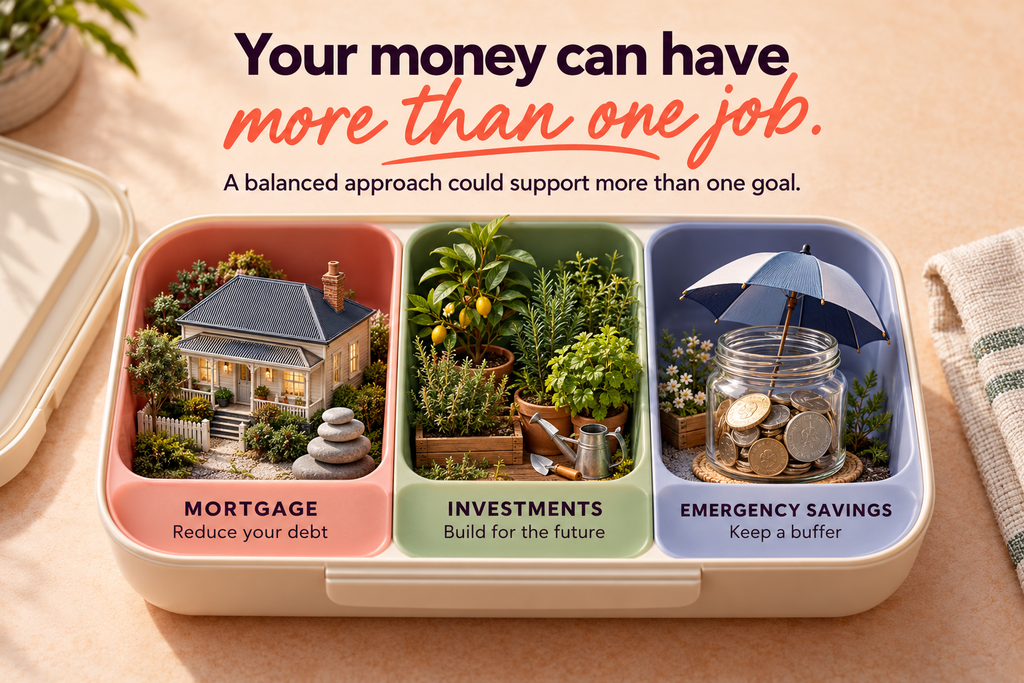
Can You Invest and Pay Down Your Mortgage Together?
Yes. You can divide available money between additional repayments and long-term investing while keeping emergency savings intact.
For example, a household with $500 genuinely available each month might put $300 towards its mortgage and $200 into investments. This is an illustration, not a recommended allocation. The right split depends on your financial position.
A combined approach can help you reduce debt while establishing an investment habit. Its trade-off is that neither goal progresses as quickly as it would if you directed all available money towards it.
Automating affordable contributions can improve consistency. Review the allocation when your mortgage rate changes, income shifts or a major goal approaches, rather than reacting to every market headline.
How to Make a Decision That Fits Your Household
Start by recording your mortgage balance, interest rate, remaining term and extra repayment conditions. Then list your emergency savings, other debts and upcoming expenses.
Define your goal: becoming mortgage-free sooner, funding retirement, building accessible assets, or balancing several priorities. Establish when you need the money and how much loss you could withstand.
Next, compare mortgage interest savings with realistic investment outcomes after tax and fees. Include a disappointing investment scenario and a future mortgage rate change. A strategy should remain workable when conditions are less favourable than expected.
Finally, consider how you will follow the plan. A modest strategy you can maintain may serve you better than an ambitious one that repeatedly forces you to borrow money back.
Frequently Asked Questions
Is paying down a mortgage a guaranteed return?
It creates interest savings based on your loan balance, rate and terms. People often compare this with a return equal to the mortgage rate, but future rates and repayment charges can change the benefit. It is a cost saving rather than investment income.
Should I invest if investment returns could exceed my mortgage rate?
Potentially, but compare returns after tax and fees and allow for risk. An expected investment return is not promised. Your timeframe, emergency savings and ability to absorb losses are equally relevant.
Can I make extra repayments on a fixed mortgage?
Often yes, within lender-specific limits. Larger repayments may attract an early repayment charge. Confirm the rules for your particular loan before transferring money.
Should I use all my savings to reduce my mortgage?
Usually you should first identify money needed for emergencies and upcoming expenses. Funds paid into a standard mortgage may be difficult to access again. A broker can explain whether a suitable structure provides flexibility.
Is it better to clear the mortgage before retirement?
Reducing debt can lower pressure on retirement income, but the decision also depends on savings, pension income, expenses and liquidity. Paying off the mortgage while leaving too little accessible money can create a different problem.
Does paying down my mortgage increase my home’s value?
No. It reduces the debt secured against the property. If the property value stays unchanged, your equity rises by the amount repaid. The home’s market value can still rise or fall independently.
Speak With a Mortgage Broker About Your Next Step
Choosing whether to invest or pay down your mortgage starts with understanding your current loan. A mortgage broker can review your repayment options, explain extra payment limits and help assess a structure that fits your cash flow.
Bring your loan details, income and expenses, savings balance and financial goals. Ask for a clear comparison of repayment scenarios, including relevant fees and the effect on your loan term.
Speak with a mortgage broker↗ to discuss how your home loan can support your wider financial goals. For investment selection or tax planning, seek advice from the relevant qualified professional.

