

Your mortgage does not necessarily have to be one large loan on one interest rate. The way your lending is structured can affect repayment certainty, flexibility and how easily you can use savings or make extra repayments.
What Does Mortgage Structure Mean?
Your mortgage structure is simply the way your home loan is organised. Depending on the lender and your circumstances, your lending may include fixed, floating, split, offset or revolving credit portions.
The important point is that the lowest advertised rate is not the only consideration. Your income, savings, spending habits, future plans and need for repayment certainty can all influence which features may suit you.
1. Fixed-Rate Mortgage
With a fixed-rate mortgage, the interest rate is fixed for an agreed period. This can make repayments easier to budget for because the rate does not change during that fixed term.
The trade-off is flexibility. Depending on the loan terms, there may be limits or costs associated with making large additional repayments, restructuring the loan or repaying it early.
Related guide: Should You Fix Your Mortgage for 1, 2, 3 or 5 Years?
2. Floating-Rate Mortgage
A floating mortgage has an interest rate that can change over time. This means repayments can move as the interest rate changes, but floating lending can also provide greater flexibility for some borrowers.
For example, someone who expects to make lump-sum or additional repayments may value flexibility more than someone whose priority is having predictable repayments.
3. Splitting Your Mortgage
You do not necessarily have to choose between having everything fixed or everything floating. A split mortgage divides the lending into separate portions.
Simple example only
$300,000 fixed for one term
$200,000 fixed for another term
$100,000 floating or in another flexible structure
A split structure can provide a combination of certainty and flexibility. It can also mean that not all of your lending reaches the end of its fixed period at exactly the same time.
4. Offset Mortgage
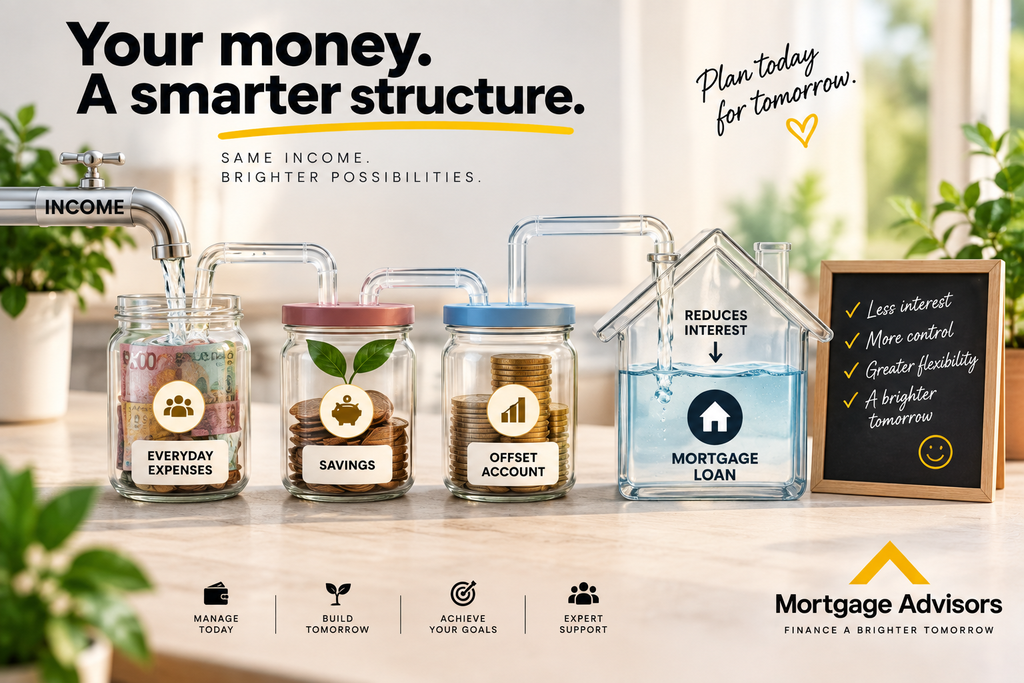
An offset mortgage can be useful for borrowers who maintain savings. Eligible savings or transaction account balances are linked to the relevant home-loan portion and used to reduce the balance on which interest is calculated.
Example
Offset mortgage: $100,000
Linked savings: $30,000
Interest calculated on: $70,000
The savings remain accessible, while the money held in the linked accounts can help reduce interest on the relevant loan portion.
Related guide: How Much Should You Keep in an Emergency Fund Before Buying a Home?
5. Revolving Credit
A revolving credit mortgage works more like a large transactional credit account. Income can be paid into the account and expenses withdrawn from it, while interest is generally calculated on the outstanding balance.
This can provide flexibility, but it also requires discipline. If available credit is repeatedly spent again, reducing the mortgage balance can become more difficult.
The Lowest Rate Isn’t the Whole Decision
Two borrowers can receive the same mortgage rate and still have very different needs. One may have a stable salary and prefer predictable repayments. Another may receive irregular income or occasional bonuses and want more flexibility to make extra repayments.
That is why mortgage structure should consider how you actually manage your money, not simply today’s advertised interest rate.
Questions to Ask Before Choosing a Structure
- How predictable is my income?
- How important are predictable repayments to me?
- Do I regularly keep money in savings?
- Am I likely to receive bonuses or other lump sums?
- Do I want to make additional repayments?
- Could my household income or expenses change?
- How disciplined am I with access to available credit?
- What are my plans for the property over the next few years?
Your Mortgage Structure Can Change Over Time
The structure that suits you today may not suit you several years from now. Your income could increase, your savings may grow, your family circumstances may change, or you may decide to purchase another property.
This is why it can be useful to review your structure when your circumstances change or when fixed portions are approaching expiry.
First-Home Buyers
For first-home buyers, manageable repayments and a structure that is easy to understand can be particularly important. Before concentrating on more complex features, consider how comfortably the repayments fit within your budget and how much flexibility you genuinely need.
Related guides: What Is Pre-Approval and Why Is It Important? · pre-approval vs Full Mortgage Approval · How Long Does Mortgage Pre-Approval Last?
Refinancing Homeowners
Refinancing can also be an opportunity to review mortgage structure rather than focusing only on obtaining a different interest rate. Changes in income, savings, debts or future plans could mean your original structure no longer fits as well.
Existing fixed lending should be reviewed carefully because early repayment or restructuring may involve costs depending on the terms of the loan.
Frequently Asked Questions
Can I split my mortgage between different fixed terms?
Depending on your lender and loan products, a mortgage may be divided into multiple portions with different terms.
Can part of my mortgage be fixed and part floating?
Potentially, yes. A split structure can combine different loan portions to provide a mixture of certainty and flexibility.
What is the difference between offset and revolving credit?
An offset structure generally keeps linked savings accounts separate and uses their balances to reduce the amount on which mortgage interest is calculated. Revolving credit operates more like a flexible transactional credit account.
Can I change my mortgage structure later?
Potentially, but the terms of your existing lending matter, particularly where fixed-rate portions may have early repayment or restructuring costs.
Is there one mortgage structure that is best for everyone?
No single structure suits every borrower. Income, savings, repayment preferences, financial habits and future plans all need to be considered.
Talk to Mortgage Advisors
Choosing a mortgage is not only about how much you borrow. How that borrowing is structured can affect your repayments and flexibility over time. Talk to Mortgage Advisors about home-loan structures and options that may suit your circumstances.

