

Cut waste, not the life you enjoy. A practical NZ guide to reviewing household costs, debt, everyday spending and your mortgage.
Reducing household expenses does not have to mean cancelling everything you enjoy. The smarter approach is to identify spending that adds little value, then review the biggest recurring commitments in your household budget.
Reducing household expenses does not have to mean cancelling every subscription, giving up takeaway coffee, staying home every weekend or completely changing the way your family lives.
For many New Zealand households, the better approach is to look at where your money is going, identify expenses that provide little value, and make smarter changes to the larger costs in your budget.
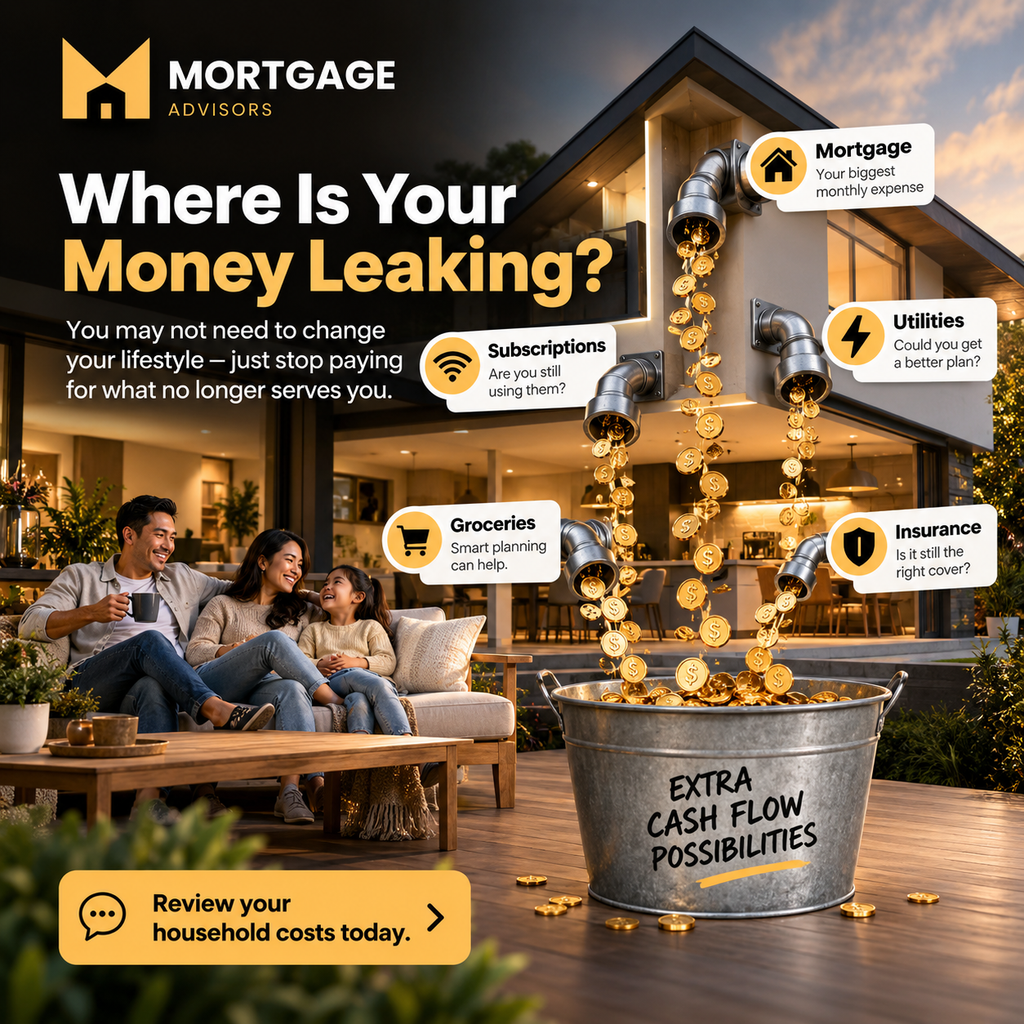
A few dollars saved here and there can certainly help. But reviewing larger commitments—such as your mortgage, personal debt, utilities, insurance and regular household bills—can potentially make a much bigger difference to your monthly cash flow.
The goal should not simply be to spend as little as possible. It should be to spend more intentionally while protecting the things that matter to you and your family.
Here are practical ways to reduce household expenses without feeling as though you have put your life on hold.
1. Start With Your Actual Household Spending
Before trying to save money, you need to know where it is currently going. Many people have a rough idea of their mortgage payment, rent, electricity and grocery costs. However, smaller automatic payments can easily disappear into the background.
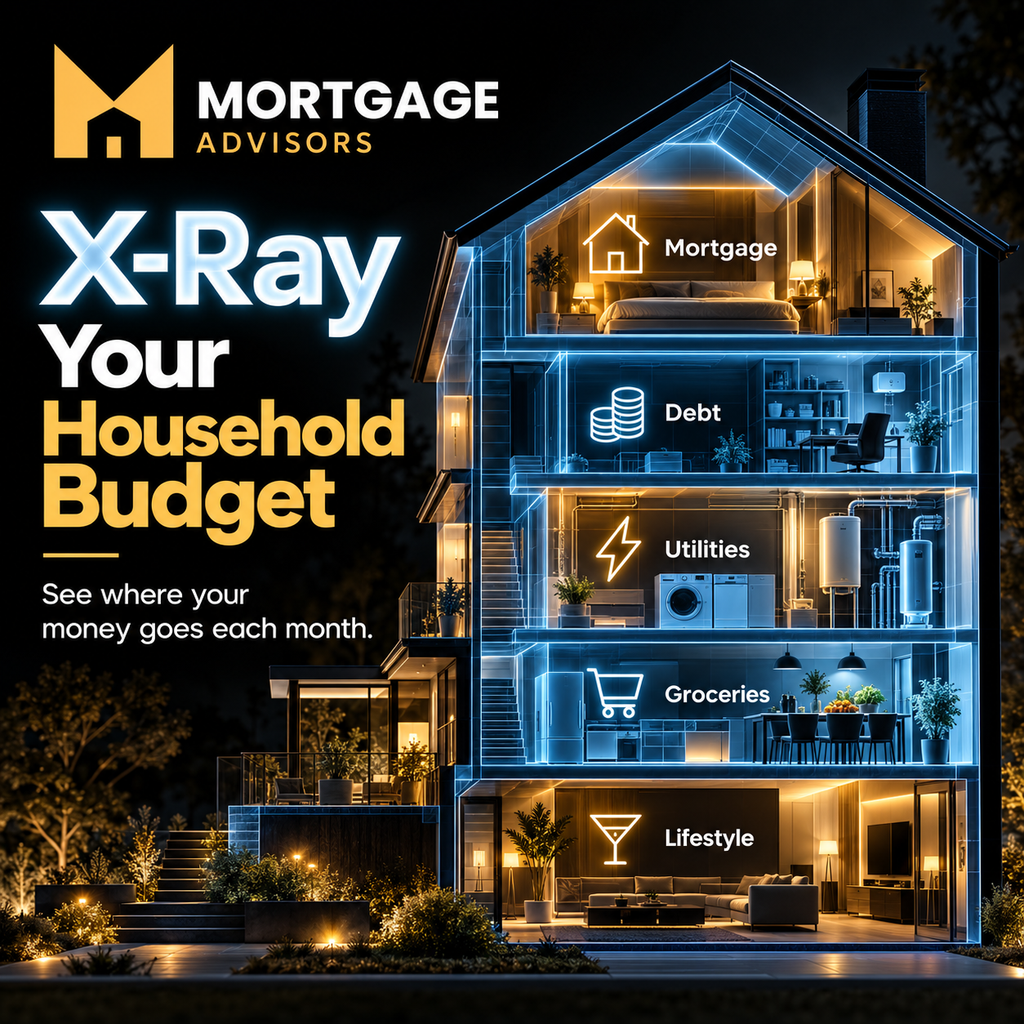
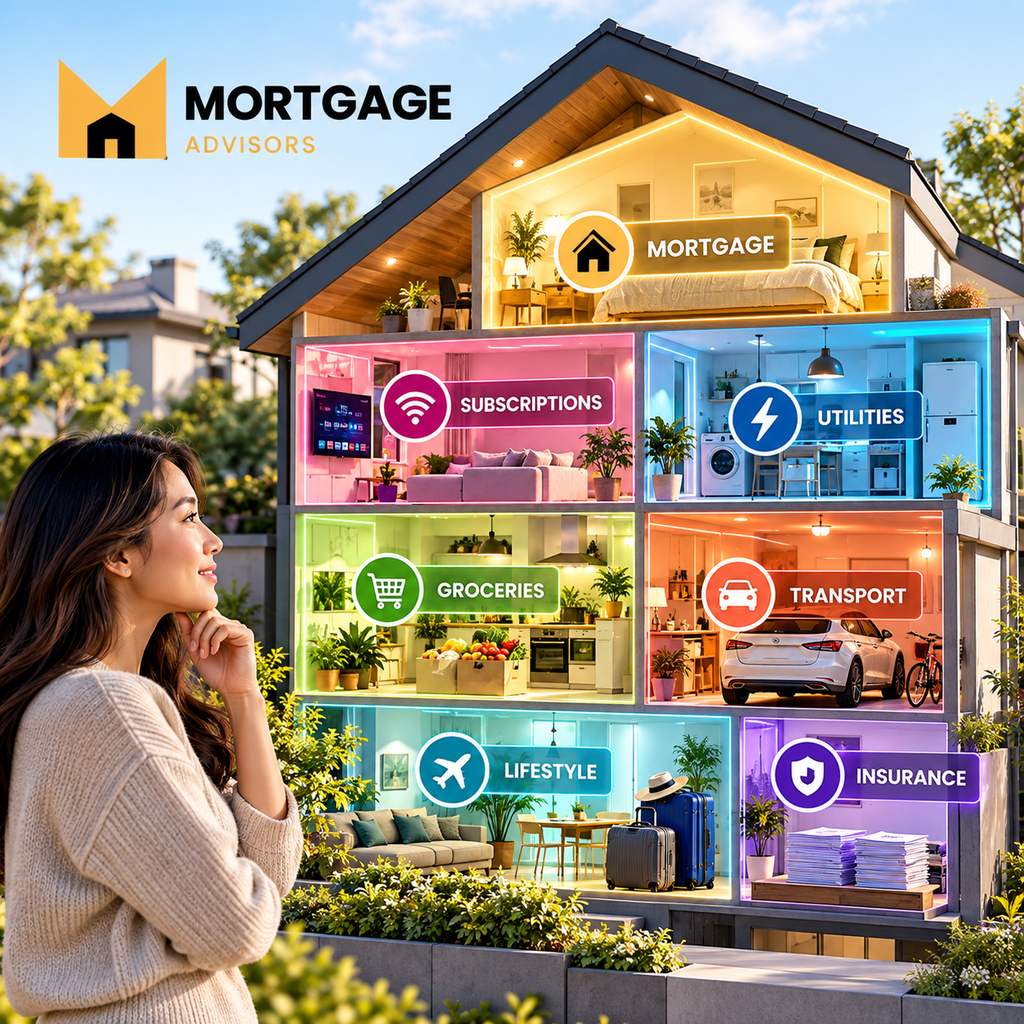
Go through the last two or three months of your bank and credit card statements and separate your spending into categories such as mortgage or rent, electricity and gas, internet and mobile plans, insurance, groceries, transport and fuel, car finance, credit cards and personal loans, streaming and subscriptions, takeaways and restaurants, entertainment, children’s activities, shopping and savings.
Focus on value rather than cutting everything
When reviewing your spending, ask: “Would I choose to pay for this again today?”
If the answer is yes, it may genuinely add value to your lifestyle. If the answer is no—or you forgot you were even paying for it—it may be an easy expense to reduce or remove. That approach makes budgeting much less restrictive.
2. Review Your Mortgage — One of Your Biggest Household Expenses
For homeowners, the mortgage is often one of the largest regular expenses. That means even a relatively small change in your mortgage arrangements can potentially have a greater impact than cutting dozens of small purchases.
Instead of only asking “How can I spend less?”, it may also be worth asking “Is my home loan still structured appropriately for my current circumstances?”
Your income, household expenses, property value, financial goals and available lending options may have changed since your mortgage was originally arranged.
A mortgage review may look at your current interest rate, fixed versus floating portions, remaining fixed-rate periods, repayment frequency, loan terms, multiple loan accounts, offset or revolving credit arrangements where appropriate, opportunities to make additional repayments and refinancing options.
Refinancing does not automatically mean you will save money, and switching lenders can involve costs or other considerations. However, reviewing your mortgage can help you understand whether your existing structure continues to suit your circumstances.
3. Look at Your Debt Repayments as a Whole
A mortgage may not be the only debt affecting your monthly budget. Some households are also managing credit cards, car loans, personal loans, store finance, hire purchase agreements and buy-now-pay-later balances.
Individually, each payment might appear manageable. Together, they can place significant pressure on household cash flow.
Could debt consolidation be worth investigating?
Debt consolidation generally involves combining several debts into one lending arrangement. This can make repayments easier to manage and, depending on the circumstances and lending terms, may change the overall cost and repayment structure.
However, consolidation needs to be considered carefully. A lower monthly repayment does not necessarily mean the debt is cheaper overall. Extending a debt over a longer period can increase the total interest paid.
The important factors include the interest rate, fees, loan term, total amount repayable, repayment discipline and whether secured lending is involved.
Related: Explore lending and debt consolidation options.
4. Reduce Grocery Costs Without Eating Boring Food
Groceries are one of the easiest expenses to lose control of because spending happens repeatedly throughout the month. You do not necessarily need to dramatically downgrade the food your household enjoys. Instead, change how you buy it.
Plan meals before shopping
A basic weekly meal plan reduces impulse purchases and helps ensure ingredients are actually used. Before going to the supermarket, check what is already in the fridge, freezer and pantry; plan several meals around those ingredients; create a shopping list; and buy what you need rather than deciding meals while walking through the supermarket.
Compare price per unit
The biggest packet is not always the cheapest option. Compare the price per kilogram, litre or item rather than looking only at the sticker price.
Keep convenience — but use it strategically
If takeaway night is something your family enjoys, you do not necessarily have to eliminate it. You could reduce takeaway from twice a week to once a week. That still preserves the lifestyle benefit while lowering the monthly cost.
5. Audit Your Subscriptions
Subscription services are convenient because they renew automatically. That is also exactly why they are easy to forget.
You may be paying for multiple streaming services, cloud storage, music subscriptions, fitness apps, software, gaming services, premium memberships, meal subscriptions, or news and media subscriptions.
Write them all down, then separate them into Use regularly / Occasionally use / Barely use. Cancel or pause the ones sitting in the third category. You may also find that your household has duplicated services—for example, two people paying separately for something that offers a family plan.
6. Review Electricity, Internet and Mobile Plans
Loyalty does not always mean you are getting the most suitable deal. Review your electricity provider, gas provider, broadband plan and mobile plan.
Check whether you are paying for more capacity or data than you actually use. The key is to reduce unused capacity rather than useful services.
7. Be Strategic About Transport Costs
Transport can represent a substantial portion of a household budget. Calculate the real monthly cost of your vehicles, including finance payments, fuel, insurance, registration, Warrant of Fitness, maintenance and parking.
This does not automatically mean selling your car. Instead, look for practical efficiencies. You might combine errands into one trip, carpool occasionally, work from home when possible, or compare insurance and servicing costs.
8. Review Insurance — But Don’t Simply Cancel Important Cover
Insurance premiums can add significantly to monthly household expenses. Review policies such as home insurance, contents insurance and vehicle insurance.
Check whether your details are still accurate, you have overlapping cover, your excess remains appropriate, and your circumstances have changed. Shopping around may also help identify alternative pricing.
However, reducing household expenses should not mean leaving yourself exposed to a financial loss you cannot comfortably absorb. Cost is only one consideration when comparing insurance.
9. Create a Separate “Lifestyle” Budget
One reason many budgets fail is because they allow nothing for enjoyment. A budget with no room for restaurants, entertainment, hobbies or shopping may be difficult to maintain over the long term.
Instead, deliberately allocate an affordable amount to lifestyle spending. Once you establish the limit, you can decide how you want to use it. That means you still enjoy your lifestyle—but you are controlling the amount rather than discovering the total at the end of the month.
10. Use Separate Accounts for Different Purposes
One simple budgeting technique is separating money according to purpose. For example, you could have accounts for household bills, everyday spending, savings and lifestyle.
This makes it easier to see whether one area is starting to exceed the budget. Automatic transfers after payday can also reduce the amount of manual budgeting you need to do.
11. Build an Emergency Buffer
Unexpected expenses are inevitable. A vehicle may need repairs. A dental bill may arrive. An appliance may stop working.
Without savings available, households sometimes rely on credit cards or personal loans to cover unexpected costs. That can turn a one-off expense into months—or years—of repayments.
Building an emergency fund gradually can help reduce your dependence on borrowing when something unexpected happens. You do not need to build a huge fund overnight. Start with an achievable target and contribute regularly.
12. Make Extra Mortgage Repayments Carefully
If your household budget improves, you may consider putting some of the savings toward your mortgage. Even modest additional repayments can reduce principal faster.
However, check your mortgage conditions first, particularly if you have a fixed-rate loan. Some lenders may limit additional repayments during fixed periods or charge costs in certain circumstances. Your adviser can help explain how your particular mortgage is structured.
13. Don’t Confuse Lower Monthly Payments With Lower Overall Costs
This is particularly important when considering refinancing or consolidating debt. A lower monthly repayment may immediately improve cash flow, but if the repayment period becomes much longer, you could potentially pay more interest overall.
Whenever you change a loan, look beyond the monthly repayment. Consider the interest rate, remaining loan term, new loan term, fees, break costs where applicable, total expected repayment and whether your financial position may change.
14. Review Your Budget After Major Life Changes
Your budget should not be something you create once and never review again. Revisit it whenever your circumstances change—such as starting a new job, receiving a pay increase, having a child, buying a home, refinancing, moving house, changing vehicles, taking on new debt, becoming self-employed, losing income or having a fixed mortgage rate expire.
Even without a major life event, reviewing household finances every few months can help identify expenses that have gradually increased.
15. Prioritise the Biggest Opportunities First
When people decide to save money, they often start with tiny expenses. There is nothing wrong with that—but consider the bigger picture.
Saving $5 per week is roughly $260 per year. Useful? Absolutely. But reviewing a major household commitment could potentially affect substantially more of your annual cash flow.
Reducing Expenses Doesn’t Mean Reducing Your Quality of Life
The most sustainable household budget is rarely the most restrictive one. You are more likely to stick with changes when they allow you to continue enjoying the things you value.
Instead of asking “What can I stop doing?”, try asking “What am I paying for that doesn’t improve my life?”
You might decide that family dinners out are important but three unused subscriptions are not. You might decide to keep your gym membership but change your phone plan. You might continue taking an annual holiday while reducing unnecessary day-to-day spending.
There is no universal household budget. The aim is to align your spending with your priorities.
Could Reviewing Your Mortgage Improve Your Household Cash Flow?
Because housing costs can make up a significant portion of household expenditure, your mortgage is worth reviewing alongside your other expenses.
Your circumstances may have changed since your loan was originally arranged. A mortgage adviser can help you review matters such as your existing home loan, repayment structure, upcoming fixed-rate expiry and potential refinancing options.
The right approach depends on your personal circumstances, current lending arrangements, financial goals and lender criteria.
Frequently Asked Questions
How can I reduce household expenses without changing my lifestyle?
Start by removing spending that provides little value rather than cutting everything you enjoy. Review subscriptions, utilities, phone plans, insurance, groceries and larger commitments such as your mortgage and other debts. Small efficiencies across several categories can add up without requiring major lifestyle changes.What household expenses should I reduce first?
Start with the largest recurring expenses because they generally offer the greatest potential impact. For homeowners, this may include the mortgage, followed by debt repayments, insurance, utilities, groceries and transport.Is refinancing a good way to reduce monthly expenses?
Refinancing may change your interest rate, repayment amount or loan structure, but it is not automatically the right choice for everyone. There can be fees, break costs and other considerations. A mortgage adviser can review your circumstances and explain available options.How often should I review my mortgage?
It can be useful to review your mortgage when a fixed term is approaching expiry, your financial circumstances change, interest rates or lender products change materially, or you are considering refinancing, restructuring debt or making additional repayments.Is debt consolidation a good way to reduce household expenses?
Debt consolidation may make several repayments easier to manage and can change monthly cash flow. However, extending the repayment term can increase total interest costs, so interest rates, fees, security and loan duration should all be considered.Should I cancel all subscriptions to save money?
Not necessarily. Keep subscriptions you regularly use and value. Focus first on duplicated services, forgotten subscriptions and services you rarely use.How much should I keep in an emergency fund?
There is no single amount that suits every household. Your target will depend on your expenses, employment situation, dependants and financial circumstances. The important thing is to begin building a buffer that can help cover unexpected costs without automatically relying on debt.Can a mortgage broker help me lower my household expenses?
A mortgage broker does not manage every part of a household budget, but they can review your mortgage and relevant lending arrangements. They may be able to explain refinancing, repayment structures, fixed-rate options and other lending solutions based on your circumstances.
In this guide
Start with actual spendingReview your mortgageLook at debt as a wholeGroceriesSubscriptionsUtilities & mobileTransportInsuranceLifestyle budgetEmergency bufferFAQs
Could your home loan still be working harder for you?
Review your current mortgage structure, upcoming fixed-rate expiry or refinancing options with a mortgage adviser.
Review the big costs before cutting the little joys.
If you would like to review your mortgage, discuss refinancing or better understand your current lending structure, Mortgage Advisors can help you explore options based on your circumstances and goals.

