

A practical guide to creating a financial buffer while continuing to manage your home loan and everyday household expenses.
Owning a home can bring a sense of stability, but it also comes with financial responsibilities that can sometimes arrive without much warning.
The hot water cylinder stops working. Your car suddenly needs repairs. An unexpected medical or dental bill appears. Your income changes. Or a major household expense lands at the same time as your mortgage repayment.
When you already have a home loan to manage, finding extra money for emergencies can feel difficult.
That is exactly why having an emergency fund can be useful.
An emergency fund is money set aside specifically for unexpected and necessary expenses. It gives your household a financial buffer so that one surprise bill does not immediately have to go on a credit card, personal loan or other form of borrowing.
The challenge for many homeowners is simple: how do you build emergency savings while continuing to pay your mortgage and your normal household expenses?
The answer does not necessarily involve making huge changes overnight. For many households, it is about starting with a realistic target, making saving automatic and gradually building a buffer that suits your circumstances.
What Is an Emergency Fund?
An emergency fund is a pool of money kept aside for expenses that you did not reasonably plan for.
It is different from money you are saving for holidays, Christmas, home renovations, a new vehicle, furniture, investments or entertainment. Those are known expenses or financial goals.
An emergency fund is designed for unexpected situations such as urgent home repairs, essential vehicle repairs, unexpected medical costs, a temporary reduction in household income, an urgent insurance excess or an essential appliance replacement.
The purpose is not to predict every possible emergency. It is to give yourself some breathing room when something unexpected happens.
Why Is an Emergency Fund Important When You Have a Mortgage?
A mortgage is usually one of the largest regular financial commitments a household has.
Unlike some flexible expenses, your mortgage repayment generally cannot simply be ignored for a month because another bill has appeared.
That means homeowners often have less room to absorb unexpected costs.
Example: if your household is already covering mortgage repayments, insurance, groceries, power, transport, childcare and other debt repayments, a sudden $1,500 car repair can place immediate pressure on the rest of the budget.
Without savings, you may need to use a credit card or take on additional debt. With an emergency fund, you may be able to deal with the expense without immediately increasing your borrowing.
How Much Should You Have in an Emergency Fund?
There is no single amount that works for every household. Your own target should reflect your financial situation.
Consider factors such as whether your household relies on one income or two, how stable your income is, your mortgage repayment amount, whether you have children, your insurance cover, your existing debt and how easily you could reduce spending if necessary.
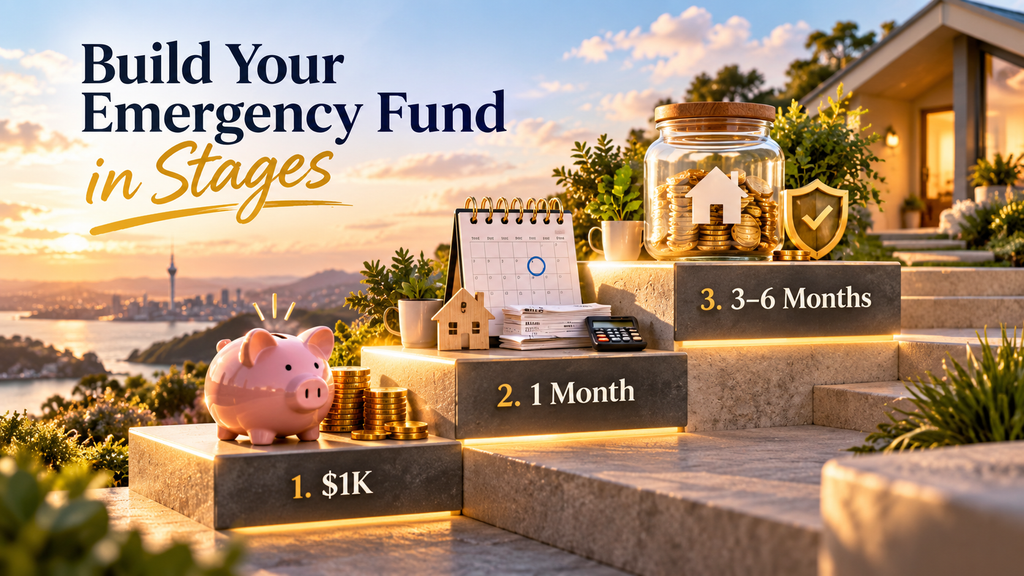
Rather than focusing immediately on a very large number, it can be easier to build your fund in stages.
Start With Your Real Household Budget
Before deciding how much to save, understand where your money is currently going.
Look at your last two or three months of spending and separate expenses into broad categories.
Essential expenses
- Mortgage repayments
- Rates and insurance
- Groceries and utilities
- Transport
- Childcare
- Minimum debt repayments
Flexible expenses
- Takeaways and dining out
- Entertainment
- Shopping
- Streaming subscriptions
- Hobbies and holidays
If you already use a budgeting framework such as the 50/30/20 budget rule, your emergency fund may sit within the savings and financial goals portion of your budget.
Pay Yourself First
One of the simplest ways to build an emergency fund is to treat saving as a regular household expense.
Instead of waiting until the end of the month to see what is left, transfer money into savings shortly after you are paid.
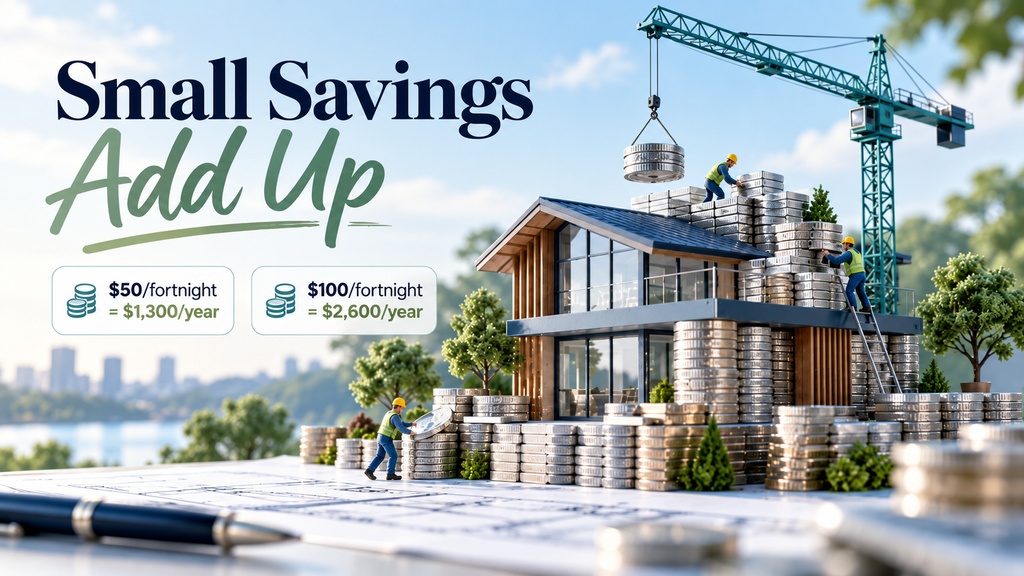
For example, if you are paid fortnightly and automatically transfer $50 each payday, that becomes approximately $1,300 over a year. At $100 per fortnight, it becomes approximately $2,600 over a year.
The amount does not have to be large. Consistency often matters more than starting with an ambitious target you cannot maintain.
Automate Your Emergency Savings
Automation can make saving easier because you do not have to make the same decision every payday.
You could set up an automatic payment from your everyday account into a separate emergency savings account.
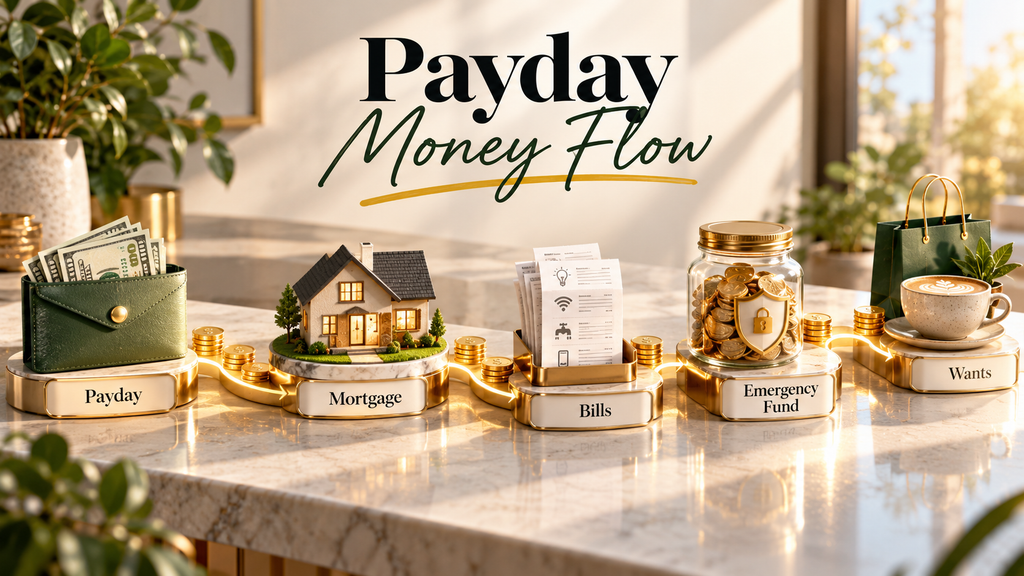
Simple flow: Payday → Mortgage → Bills → Emergency Fund → Wants
Even a relatively small automatic amount can gradually build into a meaningful buffer. You can always increase the amount later.
Keep Your Emergency Fund Separate
Your emergency fund should generally be easy to access, but not so easy that you regularly spend it.
Keeping it in the same account as your everyday spending can make it difficult to tell what is genuinely available.
Consider keeping it in a separate savings account and giving it a clear name such as Emergency Fund — Do Not Spend.
What Counts as an Emergency?
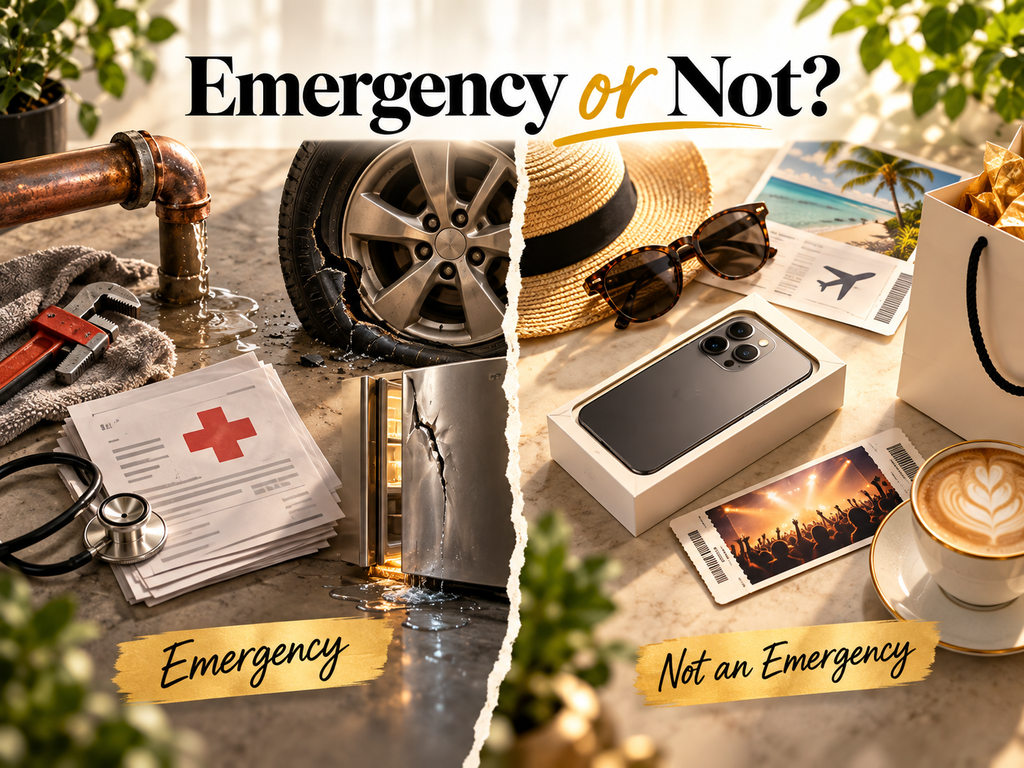
Not every unplanned purchase is an emergency.
A genuine emergency might include a major plumbing leak, urgent electrical repairs, essential vehicle repairs required for work, unexpected medical treatment, a temporary loss of income or replacing a broken fridge.
A spontaneous holiday, a phone upgrade, concert tickets, a shopping sale or furniture you would simply like to replace would usually be better treated as normal discretionary spending or a separate savings goal.
Ask yourself: Is this unexpected, necessary and urgent?
Create Separate Funds for Predictable Costs
Some expenses feel like emergencies simply because they do not happen every month. However, many of them are actually predictable.
- Car registration and servicing
- Insurance premiums
- Rates
- School costs
- Christmas
- Home maintenance
If you expect annual car costs to total $1,200, for example, you could set aside around $100 per month in a separate account.
Should You Save or Make Extra Mortgage Repayments?
If you have spare money each month, should it go towards your emergency fund or your mortgage?
There is no universal answer.
Making additional mortgage repayments may help reduce your loan balance and potentially reduce the amount of interest you pay over time. However, money paid into your mortgage may not always be as easily accessible as cash in a savings account, depending on how your home loan is structured.
A simple approach might be to build a small emergency buffer first, continue making your required mortgage repayments, build your emergency savings further, and then review whether additional mortgage repayments are appropriate.
Before making significant additional mortgage payments, check your loan terms. Fixed-rate mortgages in particular may have restrictions or costs associated with additional repayments
What About Revolving Credit or Offset Mortgages?
Some home-loan structures may allow savings to work alongside your mortgage.
Depending on your lender and loan structure, revolving credit or offset arrangements may allow cash balances to reduce the amount of mortgage interest calculated.
However, these structures require discipline. If savings remain easily accessible, some borrowers may find themselves spending money that was originally intended for emergencies.
Look for Small Amounts Before Making Big Cuts
Building an emergency fund does not necessarily require completely changing your lifestyle.
Start by reviewing smaller recurring expenses such as unused subscriptions, takeaway spending, delivery fees, impulse purchases, multiple streaming services or an expensive mobile plan.
If you find $30 per week that could be redirected into savings, that could amount to approximately $1,560 over 12 months.
Redirect Windfalls Into Your Emergency Fund
Your regular salary does not have to do all the work.
Consider directing part of unexpected or irregular income into your emergency fund, including tax refunds, bonuses, overtime, commission, gifts, money from selling unused household items or additional income.
You do not necessarily have to save all of it. For example, you might decide that whenever additional money arrives, 50% goes to your emergency fund and 50% can be used elsewhere.
Increase Your Savings When Your Expenses Drop
Your household expenses will change over time. Perhaps you finish paying a vehicle loan, a childcare expense ends, you receive a salary increase or you cancel a major subscription.
Rather than allowing the entire difference to disappear into everyday spending, redirect some of it into your emergency fund.
What If Your Mortgage Already Takes Up Most of Your Income?
Some homeowners may find that their mortgage and other essential expenses already use a significant portion of their income.
In that situation, saving aggressively may not be realistic.
Start with an amount you can actually maintain — even $10 per week, $25 per fortnight or $50 per month can be a beginning.
You may also want to review your wider household budget and mortgage structure.
Review Your Mortgage When Your Circumstances Change
Your emergency fund and your mortgage should not necessarily be considered completely separate from your wider financial position.
If your fixed rate is about to expire, your income has changed, household expenses have increased, you have several debts or you want to review your loan structure, it may be useful to review your mortgage.
A mortgage review does not automatically mean changing lenders. It may simply give you a clearer understanding of whether your current home-loan structure still suits your circumstances.
A Simple Emergency Fund Plan for Homeowners
- Calculate one month of essential expenses.
- Choose your first target. For example, $1,000.
- Choose a regular contribution. Perhaps $50 per fortnight.
- Automate the transfer.
- Keep the money separate.
- Review every three to six months.
- Refill the fund after using it.
Frequently Asked Questions
1.How much emergency savings should a homeowner have?
There is no single correct figure. Your ideal emergency fund depends on your income, mortgage payments, household expenses, job stability and other financial commitments. Starting with a smaller target such as $1,000 and gradually increasing it can make the goal more manageable.
2.Should I build an emergency fund before paying extra on my mortgage?
Many homeowners prefer to maintain some accessible emergency savings before committing all spare money to additional mortgage repayments. The appropriate balance depends on your circumstances and mortgage structure.
3.Can I use my emergency fund to pay my mortgage?
If you experience an unexpected loss or reduction in income, maintaining essential commitments such as your mortgage may be one reason you have an emergency fund. If you are experiencing ongoing repayment difficulty, contact your lender or adviser early rather than relying indefinitely on savings.
4.Where should I keep my emergency fund?
Many people use a separate savings account that is accessible when genuinely required but kept apart from everyday spending.
5.Is $1,000 enough for an emergency fund?
It may be a useful starting point, but it may not cover a major emergency or extended loss of income. You can treat $1,000 as your first milestone and gradually increase your savings from there.
6.Should I use my emergency fund for home maintenance?
Unexpected urgent repairs may qualify as an emergency. Routine and predictable maintenance is better planned for separately where possible.What happens if I cannot afford to save much?
Start small. Even a modest, consistent amount can gradually build a financial buffer. Review the amount whenever your income or expenses change.
Final Thoughts
Building an emergency fund while paying a mortgage can feel difficult because there are always competing priorities.
The mortgage needs to be paid. Bills continue arriving. You may also be saving for holidays, children, home improvements or long-term goals.
That is why the goal does not need to be perfection.
Start by creating a small buffer. Automate what you can. Separate emergency savings from everyday spending. Increase the amount when your circumstances allow.
Over time, that emergency fund can give you another layer of financial resilience alongside your home.
Speak With a Mortgage Adviser
If you are reviewing your household budget, approaching the end of a fixed mortgage term, considering refinancing or simply want to understand your current home-loan structure, speaking with a mortgage adviser can help you understand your options.
Mortgage Advisors
0800 93 0000

