

Your mortgage may have suited you when it was first arranged. But your income, plans, property and financial priorities can change. A mortgage review helps you check whether your home loan still fits where you are today.
Getting a mortgage isn’t necessarily something you do once and then forget about for the next 20 or 30 years. Your income can change, your family may grow, interest rates move, and your property value and future plans may change.
One useful question to ask:
Does my mortgage still suit my current financial position and future plans?
The better prepared you are for the review, the easier it can be to understand your options.
What Is a Mortgage Review?
A mortgage review is a closer look at your existing home lending. Rather than focusing only on your current interest rate, a review can consider your outstanding mortgage balance, repayments, fixed and floating portions, remaining loan term, available equity and how the mortgage fits with your current circumstances.
Depending on your situation, a review might result in no change at all. Alternatively, you might consider refixing, restructuring the mortgage, changing repayments, reviewing loan features, accessing equity or investigating refinancing with another lender.
The purpose isn’t simply to find a different mortgage. It’s to understand whether your current mortgage is still appropriate for where you are now.
When Should You Review Your Mortgage?
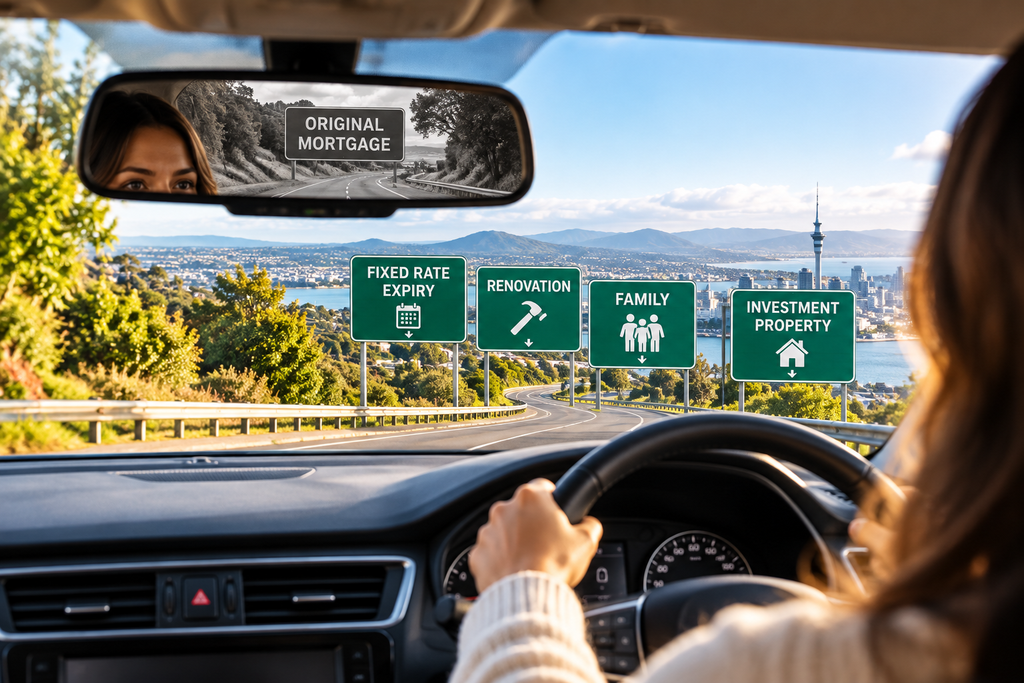
There is no single time that suits every homeowner. A fixed rate approaching expiry, a change in income or household circumstances, renovations, a major purchase, or plans for another property can all provide a natural opportunity to review your lending.
1. Find Out Your Current Mortgage Balance
Start with the basics. Check exactly how much you currently owe through online banking or your latest mortgage statement. If your mortgage is divided into several portions, record each balance separately so you have a clear starting point.
2. Check When Your Fixed Terms Expire
For each fixed portion, note the current interest rate, outstanding balance, fixed-term expiry date and repayment amount. If you are considering changing lenders before a fixed term expires, early repayment or break costs may also need to be considered.
3. Check Your Remaining Loan Term
Your interest rate matters, but so does the amount of time remaining on your mortgage. Extending the loan term can reduce required repayments, but it can also increase the total interest paid over time. Review both what you pay now and how long you will be paying it.

4. Review Your Income
Your financial position today may look very different from when your mortgage was originally approved. Employees may want recent payslips and details of regular additional income available. Self-employed borrowers may need business financial statements and tax information if the review leads to refinancing or additional lending.
5. Look at Your Regular Expenses
Review what is actually leaving your accounts each month, including groceries, utilities, insurance, transport, childcare, rates, subscriptions and other regular commitments. This helps you understand how much flexibility you genuinely have before changing repayments.
6. List Your Other Debts
Write down your current debts outside the mortgage, including credit cards, personal loans, vehicle finance, Buy Now Pay Later facilities, student loans and other lending. Note the balance, repayment and credit limit where relevant.
7. Check Your Savings and Emergency Fund
A mortgage review should not focus only on paying the mortgage as quickly as possible. Consider your accessible savings, emergency fund and other financial goals as part of the overall picture.
8. Understand Your Approximate Equity Position
Having a reasonable understanding of your property’s current value can help indicate your approximate equity position. For example, a $900,000 property with a $500,000 mortgage has approximately $400,000 of equity. This does not mean the entire amount is available to borrow; additional lending remains subject to lender criteria, affordability and applicable LVR requirements.
9. Think About What You Actually Want to Achieve
Instead of beginning with only “Can I get a better interest rate?”, think about what you want your mortgage to do for you. You might want to reduce interest costs, pay the mortgage off sooner, create more flexibility, improve cash flow, prepare for renovations, access available equity or consider another property purchase.
10. Check Whether Your Current Loan Features Still Suit You
Depending on your lender and product, your mortgage may include fixed lending, floating lending, revolving credit, offset accounts or additional repayment options. Your financial habits may have changed, so it is worth considering whether your current structure still works for you.
11. Think About What’s Coming Next
A good mortgage review should not only look backwards. Think about the next 12–24 months. A new baby, parental leave, a job change, renovations, another vehicle, an investment-property purchase or a move into self-employment can affect how much flexibility you want from your mortgage.
12. Gather Your Mortgage Information
Start with your current mortgage statement, fixed-rate details, income information, existing debt details and relevant property information. If you are self-employed or considering new lending, further financial information may be required. Your mortgage adviser can tell you what is needed based on what you want to achieve.

Questions to Ask During Your Mortgage Review
Does my current mortgage structure still suit me? What happens when my fixed rate expires? Should I split the mortgage? Would increasing repayments make a meaningful difference? Could an offset or revolving-credit facility suit me? What would refinancing cost? What is my approximate equity position? These are all useful questions to explore during a review.
Mortgage Review vs Refinancing
A mortgage review does not automatically mean changing banks. It is the process of looking at your current lending and considering your options. You may decide to keep your existing structure, refix, restructure, increase repayments, make a lump-sum payment, investigate refinancing or consider additional lending.
Frequently Asked Questions
What should I bring to a mortgage review?
Start with your current mortgage balances, interest rates, fixed-term expiry dates and repayments. Depending on what you are considering, updated income, expenses, debts and property information may also be useful or required.
Should I review my mortgage before my fixed rate expires?
It can be useful to start before the expiry date rather than leaving the decision until the last minute. This gives you time to understand your current position and consider your options.
Does a mortgage review mean I have to refinance?
No. Refinancing is only one possible outcome. You may decide to remain with your existing lender and refix or restructure your mortgage.
Can I access equity during a mortgage review?
Potentially, but having equity does not automatically mean you can borrow it. Additional lending remains subject to lender criteria, affordability assessment and applicable LVR requirements.
Do self-employed borrowers need additional documents?
They may. If the review involves refinancing or additional lending, the lender may require business financial statements, tax information and other evidence to verify self-employed income.
Related Mortgage Guides
What Happens When Your Fixed Mortgage Rate Expires? · Mortgage Refinancing: Costs, Benefits and Potential Risks · How to Choose the Right Mortgage Structure · Should You Make Extra Mortgage Payments? · How Mortgage Overpayments Can Save You Interest
Is It Time to Review Your Mortgage?
If your fixed term is approaching expiry, your circumstances have changed, or you simply haven’t reviewed your mortgage for some time, it may be worth taking another look.
Talk to Mortgage Advisors to review your current lending, discuss your goals and understand the mortgage options available for your circumstances.

