

Your home loan preparation guide · New Zealand
Mortgage Application Checklist
Get your documents ready before you apply for a home loan
Applying for a mortgage is easier to organise when you know what to prepare. Your lender needs a clear picture of your identity, income, expenses, debts and deposit.
Use this New Zealand checklist to build your application folder. Tick off each item as you collect it, and mark anything that does not apply as N/A.
Applicant(s): ______________________________
Date prepared: ______________________________
Documents still needed: ______________________________
1. Identification
Prepare clear, current documents so the lender can verify who you are.
- ☐ Valid passport or another accepted form of photo identification. ☐ N/A
- ☐ Additional identification if requested. ☐ N/A
- ☐ Proof of your current residential address. ☐ N/A
- ☐ Visa or residency evidence, where relevant. ☐ N/A
- ☐ Evidence of a name change if your documents show different names. ☐ N/A
Tip Ask which identification combinations are accepted and whether certification is required. Do not assume a driver’s licence alone will meet every lender’s requirements.
2. Proof of Income
Collect evidence of the income you want the lender to consider.
- ☐ Recent payslips covering the requested period. ☐ N/A
- ☐ Statements showing salary or wage deposits. ☐ N/A
- ☐ IRD income information, if requested. ☐ N/A
- ☐ Evidence of overtime, bonuses or commissions, if relevant. ☐ N/A
- ☐ Supporting evidence for other income, such as rent, benefits or child support, where applicable. ☐ N/A
Tip Separate regular income from occasional payments. The lender decides which income it can include and how much weight to give it.
3. Employment Information
Prepare a short, accurate employment summary.
- ☐ Employer name and contact details. ☐ N/A
- ☐ Job title and employment start date. ☐ N/A
- ☐ Employment status: permanent, fixed-term, casual or contractor. ☐ N/A
- ☐ Employment agreement or employer confirmation, if requested. ☐ N/A
- ☐ Details of any probation period, recent job change or upcoming contract expiry. ☐ N/A
Tip Flag recent changes early so your adviser can explain what additional evidence may help.
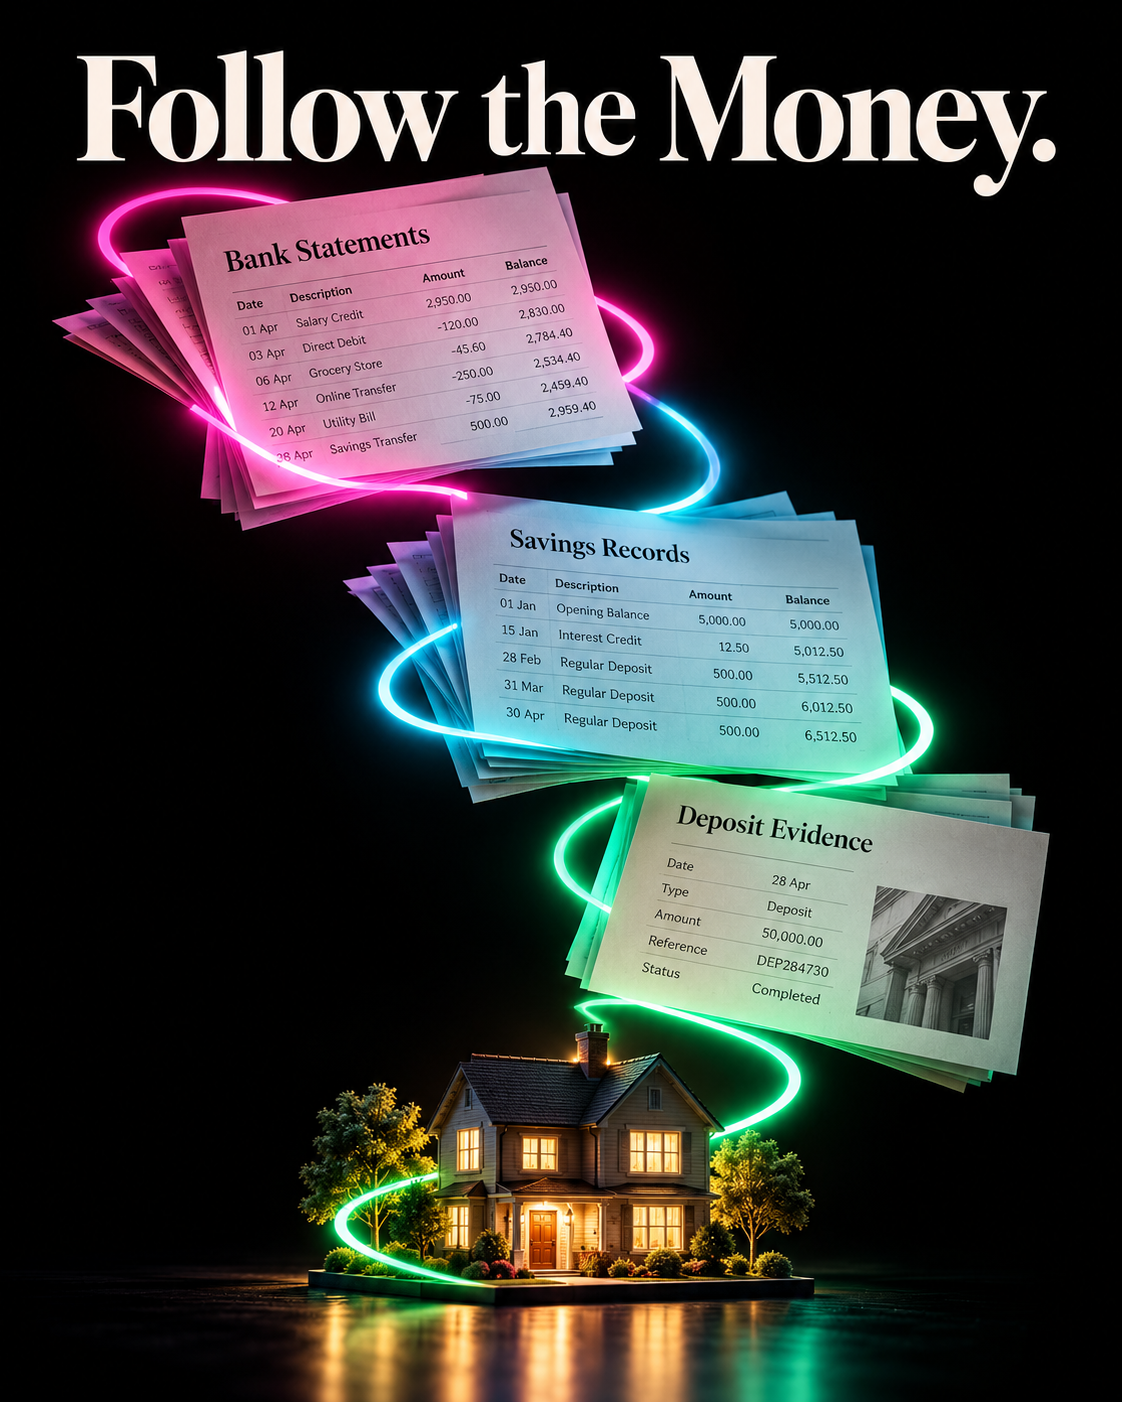
4. Bank Statements
Statements help the lender understand income and everyday spending. Three months is a common starting point, but confirm the period required.
- ☐ Complete statements for the requested transaction accounts. ☐ N/A
- ☐ Savings account statements. ☐ N/A
- ☐ Relevant joint account statements. ☐ N/A
- ☐ Statements from other banks, where requested. ☐ N/A
- ☐ Explanations and supporting evidence for unusual or large transactions. ☐ N/A
Tip Download bank-issued PDFs with your name, account details, dates and transaction history. Keep each account in a separate file and check for missing periods.
5. Existing Debts
Create a complete list of your current financial commitments.
- ☐ Personal loans and vehicle finance. ☐ N/A
- ☐ Existing mortgages. ☐ N/A
- ☐ Hire purchase and store finance. ☐ N/A
- ☐ Buy now, pay later commitments. ☐ N/A
- ☐ Student loans, overdrafts and private borrowing. ☐ N/A
- ☐ Other obligations or guarantees requested on the application. ☐ N/A
- ☐ Statements showing balances and repayment amounts. ☐ N/A
- ☐ Settlement figures or closure evidence, if a debt will be repaid. ☐ N/A
Tip Include private and overseas debts where relevant, rather than relying only on what appears in your New Zealand bank statements.
6. Credit Cards
Keep credit card information separate so no facility is overlooked.
- ☐ Latest statements for every credit card. ☐ N/A
- ☐ Credit limits as well as current balances. ☐ N/A
- ☐ Repayment details. ☐ N/A
- ☐ Details of store cards and other revolving credit facilities. ☐ N/A
- ☐ Written confirmation of any limit reduction or closure, if requested. ☐ N/A
Tip List cards even if the balance is zero. Ask your adviser how each lender assesses available credit before changing your facilities.
7. Deposit Evidence
Show both the amount available and where it came from.
- ☐ Statements showing accessible deposit funds. ☐ N/A
- ☐ Term deposit or investment records, if these funds will be used. ☐ N/A
- ☐ KiwiSaver withdrawal estimate and eligibility information from your provider, if applicable. ☐ N/A
- ☐ Gift documentation if family is contributing. ☐ N/A
- ☐ Details of any borrowed contribution. ☐ N/A
- ☐ Evidence of sale proceeds or existing property equity, if relevant. ☐ N/A
- ☐ Supporting records for overseas funds or large transfers, if requested. ☐ N/A
Tip A gift and a loan are different. Explain accurately whether any contribution must be repaid.
8. Savings History
Make it easy to follow how your deposit has accumulated.
- ☐ Statements covering the savings period requested. ☐ N/A
- ☐ Evidence of regular savings transfers. ☐ N/A
- ☐ Records explaining significant lump sums. ☐ N/A
- ☐ A brief explanation of transfers between your own accounts. ☐ N/A
Tip Moving money between accounts does not create new savings. Clear records help avoid counting the same funds twice.
9. Property Information
You can prepare your finances before choosing a property. Once you find one, ask which property documents the lender needs.
- ☐ Property address and intended use. ☐ N/A
- ☐ Proposed purchase price. ☐ N/A
- ☐ Sale and purchase agreement, when available. ☐ N/A
- ☐ Registered valuation, if required. ☐ N/A
- ☐ Property title, LIM or building report, if requested. ☐ N/A
- ☐ Body corporate information for an apartment or unit, where relevant. ☐ N/A
- ☐ Construction contract, plans and cost information for a build, where required. ☐ N/A
- ☐ Rental appraisal or tenancy information for an investment purchase, if requested. ☐ N/A
Tip Financial pre-approval does not automatically mean the lender will accept a particular property.
10. Self-Employed Documentation
Business income often needs additional explanation. Confirm the required accounting periods before asking your accountant to prepare a package.
- ☐ Accountant-prepared financial statements for the requested years. ☐ N/A
- ☐ Profit and loss statements and balance sheets, as applicable. ☐ N/A
- ☐ Relevant personal and business tax returns or IRD records, if requested. ☐ N/A
- ☐ Recent business bank statements. ☐ N/A
- ☐ Current management accounts, if requested. ☐ N/A
- ☐ Details of business debts and tax obligations. ☐ N/A
- ☐ Business ownership and trading history. ☐ N/A
- ☐ Contracts or other evidence supporting ongoing income, if requested. ☐ N/A
Tip GST returns alone do not establish net profit. Supply the financial information requested to explain business income, costs and sustainability.
11. Other Supporting Documents
Use this section for information specific to your circumstances.
- ☐ Completed application and required consents. ☐ N/A
- ☐ Household budget and dependants’ details. ☐ N/A
- ☐ Evidence of regular obligations such as childcare or child support. ☐ N/A
- ☐ Trust or company documents, if borrowing through an entity. ☐ N/A
- ☐ Guarantor information, where applicable. ☐ N/A
- ☐ Explanations of credit issues or unusual transactions, if relevant. ☐ N/A
- ☐ Any additional documents requested by the adviser or lender. ☐ N/A
Final Check Before Submission
- ☐ Each applicant has supplied their documents. ☐ N/A
- ☐ Copies are clear, complete and current. ☐ N/A
- ☐ Statements cover every requested date. ☐ N/A
- ☐ Income, debts and deposit figures match the application. ☐ N/A
- ☐ Outstanding items are clearly identified. ☐ N/A
- ☐ Documents are ready to send through the adviser’s or lender’s secure submission channel. ☐ N/A
Ready to Prepare Your Application?
You do not need to have every answer before asking for help. Start with the documents available, then work through the missing items with your adviser.
Speak with Mortgage Advisors to confirm what your application needs and organise your next steps.
Visit Mortgage Advisors ↗
