

Paying a little more than your required mortgage repayment can do more than reduce today’s balance. By reducing principal earlier, you can also reduce the amount on which future interest is calculated.
What Is a Mortgage Overpayment?
A mortgage overpayment is simply an amount paid above your required home-loan repayment. You might increase your regular weekly, fortnightly or monthly payment, or make a one-off lump-sum payment when you have additional money available.
Simple example
Required repayment: $850 per week
Chosen repayment: $900 per week
Extra repayment: $50 per week
Over 52 weeks, that extra $50 adds up to $2,600 of additional repayments, before considering the effect of interest.
How Mortgage Interest Works
Your mortgage consists of principal, which is the amount you owe, and interest, which is the cost charged for borrowing that money. When the outstanding principal is reduced, future interest is calculated against a smaller balance, all else being equal.
Lower mortgage balance → less principal exposed to interest → potentially less total interest over the remaining loan term.
This is why an overpayment can have an effect beyond the amount you pay today. It reduces principal now and can therefore reduce interest that would otherwise be charged later.
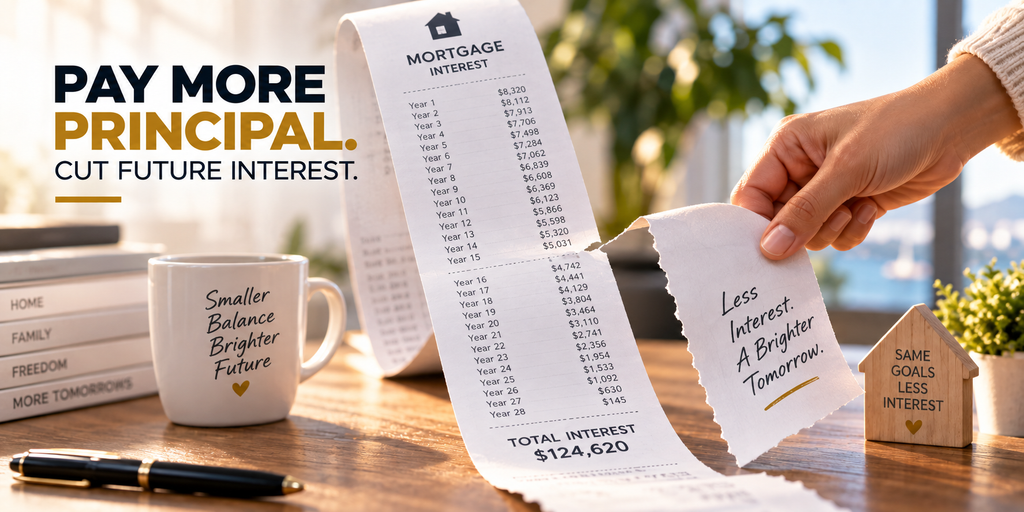
Why Overpayments Can Reduce Interest
Imagine two homeowners begin with the same mortgage balance, interest rate and remaining term. One makes only the required repayments. The other consistently pays a little extra.
At first, the difference may look small. Over time, however, the second homeowner’s principal can fall faster. Future interest is then being calculated against a lower outstanding balance than it otherwise would have been.
The important point is that you are not only paying extra today. You are reducing the amount on which future interest may be charged.
Why Paying Extra Earlier Can Matter
Timing can make a difference. Reducing principal when many years remain on the mortgage potentially gives the lower balance more time to influence future interest calculations.
Think about carrying a heavy backpack on a long walk. Removing some weight five minutes before the finish helps, but removing it near the beginning means you carry less weight for much more of the journey. Reducing mortgage principal earlier follows a similar idea.
Small Regular Overpayments Can Add Up
You do not necessarily need a large lump sum to begin reducing the balance faster. Small amounts repeated consistently can become meaningful over a year.
$20 extra per week = $1,040 per year
$50 extra per week = $2,600 per year
$100 extra per week = $5,200 per year
These figures show only the additional repayments themselves. The actual interest effect depends on your mortgage balance, interest rate, remaining term, repayment frequency and lender conditions.
Regular Overpayments vs Lump-Sum Payments
Regular overpayments
Increasing your normal repayment can suit borrowers who consistently have surplus income. It can also make the strategy easier to maintain because the extra amount becomes part of the normal household budget.
Lump-sum payments
A lump sum is a larger one-off payment. It might come from a work bonus, accumulated savings, an inheritance or sale proceeds. Both approaches can reduce principal; which is more suitable depends on your cash flow, future needs and mortgage conditions.
What Happens When Interest Rates Change?
The cost of carrying a mortgage depends partly on the interest rate applying to the loan. However, future rates are uncertain. Rather than building a repayment strategy around predicting rates, it can be useful to focus on factors you can control, including your outstanding balance, repayment amount, mortgage structure and household cash flow.
Check Your Fixed Mortgage Conditions First
Do not assume you can pay any amount into a fixed mortgage without consequences. Fixed-rate loans can have conditions around additional or early repayments. Depending on your lender, loan and circumstances, limits or early repayment costs may apply.
Before making a large overpayment, check your loan agreement or speak with your lender or mortgage adviser.
Should Every Spare Dollar Go Into Your Mortgage?
Reducing interest is useful, but accessible savings have a different purpose. If you use almost all your available cash to reduce the mortgage, an unexpected expense could leave you without a suitable financial buffer.
Consider vehicle repairs, home maintenance, insurance excesses, periods of reduced income and other unexpected costs. The aim does not necessarily need to be putting every possible dollar into the mortgage. A more balanced question is: how much can I comfortably pay extra while still maintaining enough financial flexibility?
What About Other Debts?
Your mortgage may not be your only debt. Credit cards, personal loans, vehicle finance and other consumer debts can have different interest rates, fees and repayment obligations. Looking at your complete debt position can be more useful than focusing on the mortgage alone.
How Mortgage Structure Can Affect Your Strategy
Fixed lending may provide repayment certainty but can include restrictions on additional repayments. Floating lending can provide more flexibility, although its rate can change. Some homeowners split their mortgage between different structures, while offset and revolving-credit products can allow available cash to interact with mortgage debt differently.
There is no single structure that suits everyone. Income, savings, spending habits, future plans and financial discipline all matter.
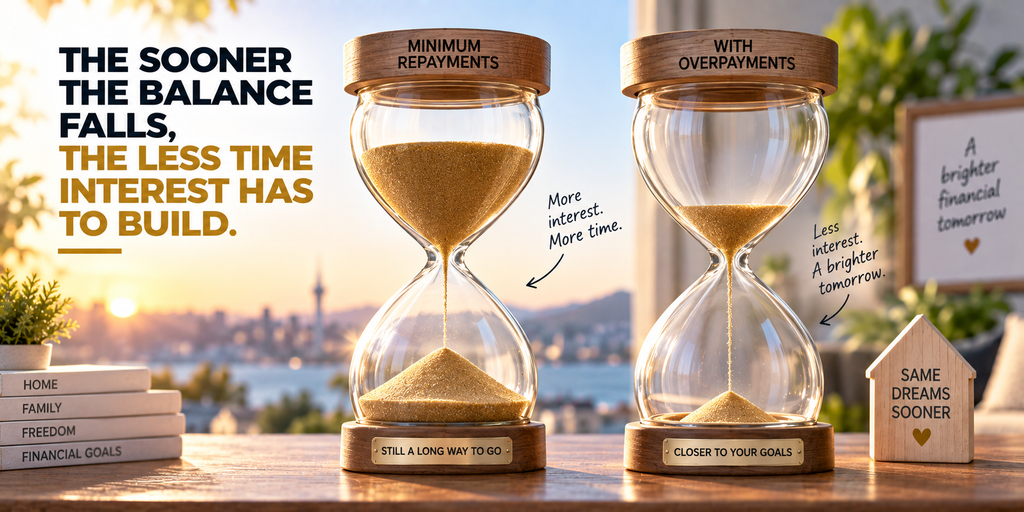
Overpayments Can Potentially Shorten the Mortgage Term
Saving interest is not the only possible benefit. If you continue paying above the required amount, the balance may reach zero earlier than originally scheduled. The exact time saved depends on the balance, interest rate, repayment frequency, size of the overpayment and future changes to the loan.
Don’t Forget Refix Time
When a fixed term ends, it can be a useful opportunity to review your repayment amount, loan structure and whether additional repayments still suit your circumstances. If your income has increased, you might compare the effect of maintaining a higher repayment rather than automatically reducing it to the new minimum required amount.
Questions to Ask Before Overpaying
- How much can I comfortably pay above the minimum?
- Does my mortgage allow additional repayments?
- Is there a limit on the amount I can repay without extra costs?
- Could an early repayment cost apply?
- Do I have enough emergency savings?
- Do I have other higher-cost debts to consider?
- Will I need this money in the near future?
- Would another mortgage structure provide useful flexibility?
- How much interest could the proposed overpayment potentially save?
- How much earlier could the mortgage potentially be repaid?
Related Mortgage Guides
Should You Make Extra Mortgage Payments?
How to Choose the Right Mortgage Structure
Fixed vs Variable Mortgage Rates: Pros, Cons and When Each Makes Sense
Should You Fix Your Mortgage for 1, 2, 3 or 5 Years?
How Much Should You Keep in an Emergency Fund Before Buying a Home?
Frequently Asked Questions
Do mortgage overpayments reduce interest?
They can. An overpayment reduces outstanding principal, which means future interest can be calculated on a lower balance. The actual saving depends on your loan details.
Is it better to overpay regularly or make a lump sum?
Both can reduce principal. Regular overpayments may suit predictable surplus income, while lump sums may suit bonuses or accumulated savings. Your loan conditions also matter.
How much does an extra $50 a week add up to?
An extra $50 per week equals $2,600 of additional repayments over 52 weeks, before considering any interest effect.
Is it better to overpay earlier?
Reducing principal earlier can potentially affect interest calculations over more of the remaining mortgage term. Your emergency savings and other financial needs should still be considered.
Can I overpay a fixed mortgage in NZ?
Possibly, but fixed loans can have restrictions or costs associated with additional or early repayments. Check the conditions applying to your specific loan first.
Should I use savings to reduce my mortgage?
That depends on what the savings are needed for. Paying down debt may reduce interest, while retaining savings provides accessible cash for emergencies and future expenses.
Could Small Changes Make a Difference to Your Mortgage?
You do not necessarily need a huge lump sum to review how quickly your mortgage is being repaid. Mortgage Advisors can help you look at your current lending structure, repayment options and goals and discuss whether additional repayments may suit your circumstances.

