

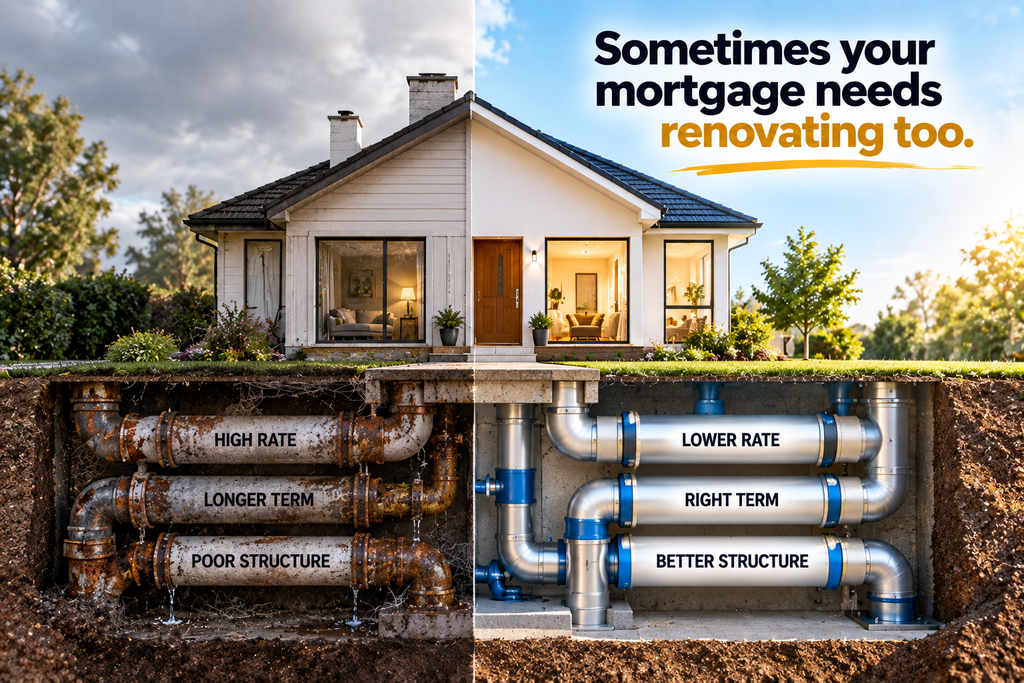
Your mortgage may have been right for you when you first bought your home. But rates, income, equity and financial goals change. A refinance review can help you understand whether your current lending still fits where you are today.
What Does Refinancing a Mortgage Mean?
Refinancing generally means replacing your existing home loan with a new lending arrangement. Often this involves moving your mortgage from one lender to another, although restructuring with your existing lender may sometimes achieve what you need.
Imagine you arranged your mortgage several years ago. Since then, your income may have increased, other debts may have reduced, your property value may have changed, or your plans may now include renovations or an investment property. The mortgage that suited you then may not be the mortgage that suits you now.
Refinancing gives you an opportunity to review the whole arrangement rather than simply continuing with the same structure because it is already in place.
Why Do Homeowners Refinance?
There is no single reason. For some homeowners, the aim is to reduce interest costs. For others, it is about flexibility, a different loan structure, consolidating eligible debts, accessing available equity or finding a lender whose products better suit their circumstances.
1. Get a More Competitive Interest Rate
Interest rates can change significantly during the life of a mortgage. If other lenders are offering more competitive options, it can be worthwhile comparing them with your existing lending.
Even a relatively small difference can matter when it applies to a large mortgage balance. However, the lowest advertised rate does not automatically mean the lowest overall cost. Break costs, legal expenses, lender fees, cashback conditions and loan features all need to be considered.
2. Change Your Mortgage Structure
Sometimes the lender is not necessarily the issue — the way the mortgage is structured may simply no longer suit you. Depending on your circumstances and available products, a mortgage could potentially include fixed lending, floating lending, revolving credit or offset facilities. Some borrowers also split their mortgage into portions with different fixed terms.
There is no single structure that suits everyone. Your income, cash flow, goals, future plans and comfort with changing interest rates all matter.
3. Consolidate Other Debts
Some homeowners investigate refinancing because they also have debts such as credit cards, personal loans or vehicle finance. In some circumstances, eligible debt may be consolidated into home lending, subject to lender approval.
Important: A lower repayment does not necessarily mean a lower total cost. Moving short-term debt into a long-term mortgage can mean paying interest on that debt for much longer, so the repayment structure matters.
4. Access Available Equity
Refinancing may also be considered when a homeowner wants to access some of the equity accumulated in a property. For example, a home worth $900,000 with a $500,000 mortgage has $400,000 of gross equity. That does not mean the full $400,000 is automatically available to borrow.
Any additional lending remains subject to lender criteria, affordability and serviceability assessments, loan-to-value requirements and the borrower’s overall financial position. Depending on the circumstances, equity may be considered for renovations, an investment property deposit, debt consolidation or another approved purpose.
When Could Refinancing Make Sense?
A mortgage review can be particularly useful when your fixed rate is approaching expiry. Instead of automatically accepting a new fixed term from your existing lender, you can use the opportunity to understand what other options may be available.
- Your fixed rate is approaching expiry. It may be a natural time to compare options.
- Interest rates have changed. Your current lending may look different against today’s market.
- Your financial position has improved. Income may have risen, debts may have reduced or equity may have increased.
- Your structure no longer suits you. What worked several years ago may not match today’s cash flow or goals.
- You are considering another property. Existing lending may need reviewing when exploring an investment purchase.
- Your lender no longer suits your needs. Products and lending policies vary between lenders.
When Might Refinancing Not Be Worth It?
Changing lenders is not automatically beneficial. If your mortgage is currently fixed at a favourable rate, leaving early could result in a break cost. There may also be legal expenses, discharge or establishment costs, and conditions attached to a previous lender cashback.
The useful comparison is not simply “Which lender has the lowest rate?” It is which option leaves you in the better overall position after the costs and features are considered.
What Does It Cost to Refinance?
Potential costs vary by lender and situation. They can include break costs on existing fixed lending, legal costs, discharge or establishment fees, repayment of previous cashback where applicable, and property valuation costs if a valuation is required.
A new lender may sometimes contribute towards certain refinancing costs or provide a cash contribution, subject to its current offer and eligibility requirements. This is why the net benefit matters more than an attractive headline rate.
How Much Could a Rate Difference Matter?
Consider a simplified example of a homeowner with a $500,000 mortgage. If another lending option had an interest rate that was 0.50 percentage points lower, a simple calculation on the opening balance would be:
$500,000 × 0.50%= $2,500
This illustrates why seemingly small rate differences can matter on a large mortgage. It does not mean the homeowner will automatically save exactly $2,500. Mortgage balances reduce over time, repayments vary, rates can change and refinancing costs need to be deducted.
A proper comparison should therefore consider the expected overall cost of each option over a relevant period rather than focusing on one advertised rate.
What Will a Lender Check When You Refinance?
Having an existing mortgage does not mean another lender will automatically approve a refinance. Moving to a new lender generally involves a new lending application.
Depending on the application, the lender may assess income and employment, living expenses, existing debts, credit history, account conduct, the property offered as security, loan-to-value ratio and overall affordability and serviceability. A refinance that looks attractive based on rates still needs to meet the new lender’s lending criteria.
Should You Stay With Your Current Bank or Switch?
Refinancing does not necessarily mean you need to leave your current bank. Before switching, it may be worth understanding whether your existing lender can offer a more suitable structure or pricing arrangement.
Staying may be simpler and could avoid some switching costs. On the other hand, another lender may provide products, features or lending policies that better suit what you are trying to achieve. Rather than comparing banks solely by interest rate, consider the complete arrangement — including structure, flexibility, fees, features and your longer-term plans.
How Can a Mortgage Adviser Help?
Refinancing can involve considerably more than searching online for the lowest advertised mortgage rate. A mortgage adviser can review your existing lending and help you understand how relevant options compare based on your circumstances.
This may include looking at your current mortgage, fixed-rate expiry dates, potential break costs, available equity, income and expenses, other debts, future property plans and different mortgage structures.
Sometimes refinancing may be appropriate. In other situations, restructuring or remaining with the existing lender may make more sense. The objective is not simply to change banks — it is to determine whether your mortgage still works effectively for you.
Frequently Asked Questions
Is refinancing the same as refixing?
No. Refixing generally means selecting a new fixed-interest period for existing lending. Refinancing generally involves replacing or restructuring lending and may involve moving to another lender.
Can I refinance while my mortgage is fixed?
Potentially. However, breaking fixed-rate lending before the end of the fixed period may result in a break cost. This should be understood before deciding whether refinancing is worthwhile.
Can I refinance to consolidate debt?
Potentially, subject to lender approval and your circumstances. Care should be taken not to unnecessarily turn short-term debt into debt repaid over a much longer mortgage term.
Can I refinance and borrow extra money?
It may be possible. Additional borrowing remains subject to available equity, lender criteria, serviceability and the proposed purpose of the funds.
When should I review my mortgage?
There is no compulsory timeframe, but a review can be worthwhile when your fixed rate is approaching expiry, your circumstances change or your future financial plans change.
Continue Reading
What Happens When Your Fixed Mortgage Rate Expires?
Fixed vs Variable Mortgage Rates: Pros, Cons and When Each Makes Sense
How to Choose the Right Mortgage Structure
Should You Make Extra Mortgage Payments?
How Mortgage Overpayments Can Save You Interest
Is It Time to Review Your Mortgage?
If your fixed rate is ending, your circumstances have changed or you simply want to understand whether your existing mortgage still suits you, Mortgage Advisors can help you review your options.

